


A homeowner discovers a burst pipe at 11 p.m. If the loss isn’t reported until the next morning, the insurer has already lost valuable time to initiate mitigation, assess exposure, and begin claim handling. During that gap, damage can continue to develop.
For claims organizations, reducing FNOL time is therefore not simply about improving intake efficiency. Earlier notification gives teams more opportunity to control claim severity, manage loss adjustment expense (LAE), identify potential coverage or recovery issues, and establish communication with the claimant sooner.
The impact of reporting lag is particularly visible in workers’ compensation. According to NCCI’s 2015 analysis, delays in reporting workplace injuries can increase claim costs by up to 51%. Claims reported more than two weeks late also showed greater attorney involvement and lower closure rates at 18 months.
Every FNOL moves through three cycles, and each one adds time. The 12 approaches in this guide address those cycles separately, from foundational practices to emerging capabilities.
Where FNOL Time Is Lost: The Three Operational Cycles
FNOL is often treated as a single intake event. A better way to look at it is as three consecutive time spans within the same claim. Each can add delay before the claims team is ready to act.
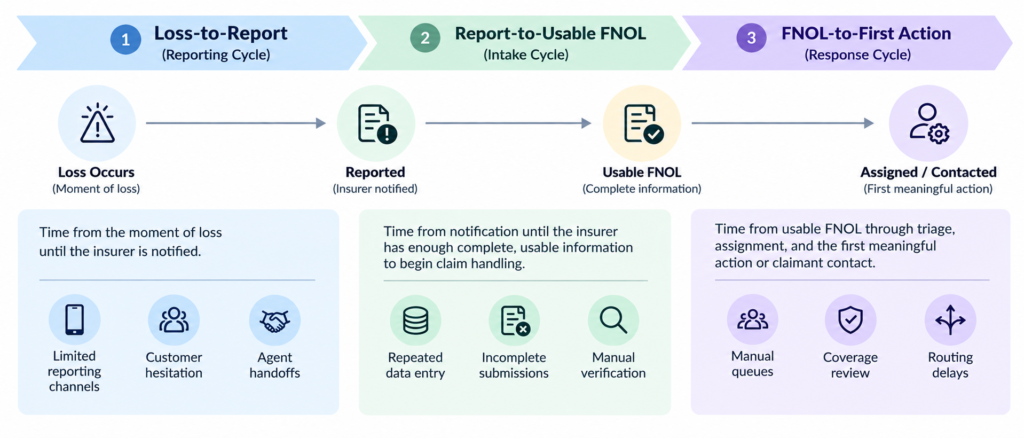
Cycle 1: Loss-to-Report
The reporting cycle begins at the moment of loss and ends when the insurer is notified. Delays can occur because of limited reporting channels, customer hesitation, agent handoffs, or a loss that happens outside normal business hours.
Cycle 2: Report-to-Usable FNOL
The intake cycle runs from notification until the insurer has enough complete, usable information to begin claim handling. Time is often lost through repeated data entry, incomplete submissions, unnecessary questions, document collection, or manual verification.
Cycle 3: FNOL-to-First Action
The response cycle begins once FNOL has been captured and continues through triage, assignment, and the first action or claimant contact. Manual queues, coverage review, routing decisions, and vendor coordination can extend this stage even when the initial report was submitted quickly.
Workers’ compensation data shows why these time gaps matter. An Integrated Benefits Institute analysis of 2.25 million workers’ compensation claims from 2010–2017 found that each additional day between injury and reporting was associated with about $50 more in total payments for medical-only claims. For indemnity claims, each additional day of reporting lag was associated with about $98 more in total payments.
We often see FNOL improvement efforts concentrate on intake because it’s the most visible stage. But delays can build before the claim reaches the insurer and again after the information has been captured.
12 Ways to Reduce FNOL Time Across the Three Claims Cycles
The following approaches address different sources of delay across reporting, intake, and response. Some are established capabilities, while others depend on newer data, automation, and AI-driven workflows.
Cycle 1: The Reporting Cycle
The reporting cycle is the first opportunity to reduce FNOL time because no downstream claims activity can begin until the loss reaches the insurer. According to J.D. Power’s 2026 U.S. Property Claims Satisfaction Study, only 38% of homeowners insurance customers reported FNOL digitally, showing that a large share of property claims still enter through channels that may involve more friction or manual handling.
The goal in this cycle is straightforward: make reporting available at the moment a loss occurs and reduce the number of handoffs between the policyholder, agent, partner, and claims system.
1: 24/7 Omnichannel Reporting
What it does
24/7 omnichannel reporting lets policyholders report a loss through web, mobile, SMS, phone, or chat without waiting for business hours or moving between disconnected channels.
Why it reduces FNOL time
It removes a basic source of delay: access. A claimant who can start FNOL immediately is less likely to wait for an agent or contact center to become available. According to J.D. Power’s 2025 U.S. Auto Claims Satisfaction Study, 26% of auto customers had deductibles of $1,000 or more, while 7% had avoided filing a claim because of concerns about a rate increase. Easier reporting won’t remove that hesitation, but it can reduce friction once a customer decides to file.
How to put it in place
Connect every reporting channel to the same claims workflow and data rules so each submission creates one consistent claim record.
Example
A restaurant owner discovers a break-in early Sunday morning. Rather than waiting for a commercial lines contact to reopen on Monday, the insured can report the loss digitally, provide the basic details, and receive a claim number immediately.
2: Partner and Agent FNOL by API
What it does
Partner and agent FNOL by API allows brokers, agents, body shops, mitigation providers, and other approved partners to submit loss information directly into the claims environment instead of sending details by email or calling a claims team.
Why it reduces FNOL time
The main benefit is fewer handoffs. When a partner already has the loss details, requiring them to pass that information to a separate intake team creates avoidable delay and increases the chance of incomplete or duplicated data. Direct submission moves the claim into the FNOL process as soon as the partner captures the required information.
How to put it in place
Define a minimum data set for each partner type, then connect partner portals or systems to the claims platform through secure APIs. Validation rules should check required fields, policy references, duplicate claims, and submission permissions before the record enters the claims workflow.
Example
After a commercial property water loss, an approved mitigation vendor can submit the initial loss details, property information, and emergency service request directly from its system. The claim enters triage without waiting for a separate email to be reviewed and manually re-entered.
3: Event-Driven FNOL
What it does
Event-driven FNOL uses connected data sources such as vehicle telematics and smart-home sensors to detect a potential loss and automatically trigger, prefill, or prompt the reporting process.
Why it reduces FNOL time
This approach shortens the reporting cycle by reducing dependence on the policyholder to initiate contact. A crash signal, water-leak alert, freeze warning, or fire-related sensor event can create an immediate notification path, giving the insurer an earlier opportunity to confirm the loss and begin the appropriate claims workflow.
How to put it in place
Insurers need reliable event data, policy matching logic, consent controls, and rules that determine when an event should create a claim, open a draft FNOL, or simply prompt the insured to respond. Thresholds should be calibrated carefully so routine events don’t generate unnecessary claims activity.
Example
A connected vehicle detects a significant collision and transmits an event signal within seconds. The system can match the vehicle to the policy, pre-populate available information, and prompt the driver to confirm the loss rather than relying on a later phone call to start FNOL.
Watch out for
This technology is already in production at some large US carriers, but adoption across the broader P&C market remains early.
4: Proactive Catastrophe Outreach
What it does
Proactive catastrophe outreach uses storm-path, hail, wind, and other event data to identify policyholders who may have been affected and contact them before they initiate a claim.
Why it reduces FNOL time
During catastrophe events, reporting delays often increase because contact centers become overloaded and policyholders may not know what information they need to provide. Targeted outreach can shorten that gap by prompting likely affected customers to confirm damage through a digital FNOL path rather than waiting for them to find the correct reporting channel.
How to put it in place
Insurers need reliable catastrophe data, geocoded policy information, and rules for determining which policyholders should receive outreach. Messages should direct customers to a simple reporting flow and make it clear that outreach identifies possible exposure rather than assuming a covered loss has occurred.
Example
After a severe hailstorm crosses a defined area, homeowners with insured properties in the affected zone receive a message asking whether they sustained damage. Customers who confirm a loss can begin FNOL immediately through a prefilled digital flow.
Cycle 2: The Intake Cycle
Once a loss reaches the insurer, the next task is turning the report into information claims teams can use. The aim isn’t to collect everything immediately. It’s to capture the right information at the right point so the claim can move forward without unnecessary intake work.
5: Prefill from Policy Data
What it does
Policy-data prefill automatically brings existing insured, policy, vehicle, property, and coverage information into the FNOL process rather than asking the claimant or adjuster to enter it again.
Why it reduces FNOL time
Re-entering information the insurer already holds adds time without improving the claim record. Prefill allows the claimant to confirm or correct existing details and spend more time providing information that is specific to the loss.
How to put it in place
Connect the FNOL workflow with the policy administration system and define which fields can be safely pre-populated, while keeping a clear way to update information that has changed.
Example
A driver reporting a parking-lot collision opens FNOL and finds the policy number, insured details, covered vehicle, and contact information already populated. The driver confirms those details and moves directly to describing the accident and damage.
6: Dynamic, Loss-Specific Questionnaires
What it does
Dynamic questionnaires change the FNOL questions based on the type of loss and the answers already provided. A windshield claim, theft loss, workplace injury, and multi-vehicle accident shouldn’t follow the same intake path.
Why it reduces FNOL time
Static forms often collect information that has little relevance to the loss while failing to ask the questions claims teams actually need. Branching logic removes unnecessary fields and surfaces follow-up questions only when a previous answer makes them relevant.
How to put it in place
Start with the minimum information required across all claims, then build question sets by line of business and loss type. Claims teams should help define the branching rules so the questionnaire reflects actual triage and assignment needs rather than becoming a longer digital form.
Example
For a workers’ compensation claim involving a lifting injury, the intake can ask about the employee’s role, injury location, treatment received, and work status. It doesn’t need to display questions designed for auto damage, third-party vehicles, or property repairs.
7: Minimum Viable FNOL
What it does
Minimum viable FNOL captures only the information required to establish the claim and move it into triage. Photos, police reports, repair estimates, witness statements, and other supporting material can follow after the claim is opened.
Why it reduces FNOL time
In our experience, intake processes are often treated as if the claim record must be complete before anyone can act. That creates delay inside the intake itself. For many losses, teams need only enough information to identify the policy, understand what happened, locate the loss, contact the claimant, and make an initial routing decision.
The remaining information can be gathered through later digital requests, adjuster follow-up, partner integrations, or third-party data. This separates claim creation from claim enrichment and allows triage and assignment to begin sooner.
How to put it in place
Define the minimum data needed to open and route a claim by line of business, then identify what can safely be collected later. Complex injury, fraud, or coverage-sensitive claims should still trigger additional upfront requirements.
Example
After a fleet vehicle accident, the insured may not yet have complete driver statements, repair estimates, or third-party documentation. The claim can still be opened with the policy, vehicle, driver, date and location of loss, known damage, and contact details while the remaining information is collected later.
Watch out for
A faster intake still needs enough information for basic fraud screening and an initial reserve; minimum viable FNOL should remove unnecessary upfront work, not essential controls.
8: Generative AI Voice Agents for FNOL
What it does
AI voice and chat support agents can handle natural phone conversations for straightforward FNOL interactions, especially after hours. For more complex calls, they can transcribe the conversation and structure key claim details for a human reviewer.
Why it reduces FNOL time
Conversational voice AI can collect initial loss information as the call happens instead of placing the claimant in a queue or requiring a callback. Unlike older IVR or scripted chatbot flows, newer systems can interpret more natural descriptions and ask follow-up questions based on the conversation.
How to put it in place
Start with well-defined, lower-complexity claim types and clear escalation rules. The system should write structured data into the FNOL workflow, preserve the call record, and transfer the claimant to a person when injury, distress, coverage uncertainty, or unusual circumstances require judgment.
Example
A homeowner calling after hours about a minor kitchen fire can describe what happened conversationally. The voice agent captures the loss location, reported damage, emergency response, and contact details, then prepares the claim for review.
Cycle 3: The Response Cycle
Once the FNOL is usable, speed depends on how quickly the claim moves into triage, assignment, and action. McKinsey has identified the potential for claims transformation to reduce loss adjustment expenses by 25–30% and indemnity spend by 3–5 percentage points. That’s a reminder of what’s at stake when early claims work still depends heavily on manual steps.
The focus here is to remove avoidable queues between intake and the first claims decision, contact, or service action.
9: Instant Acknowledgment and Proactive Status Updates
What it does
Instant acknowledgment confirms that the claim has been received, provides a claim number and next steps, and keeps the claimant informed as the claim progresses.
Why it reduces FNOL time
Acknowledgment doesn’t shorten the reporting event itself, but it reduces the gap between submission and the claimant’s first confirmation that the process has started. Proactive updates also reduce inbound status calls that can consume adjuster capacity during early claim handling.
J.D. Power’s 2026 U.S. Property Claims Satisfaction Study found that 45% of customers received claim updates digitally, indicating that digital communication is already an important part of the claims experience.
How to put it in place
Trigger acknowledgments directly from claim creation and connect later updates to real workflow events such as assignment, document requests, inspections, or vendor appointments. Because prompt-acknowledgment requirements vary by state, automated communication should support jurisdiction-specific compliance controls.
Example
An employer reports a warehouse injury online and immediately receives a claim number, next steps for submitting the medical provider’s details, and confirmation when a claims professional is assigned.
10: AI Triage at FNOL with Automated Routing
What it does
AI-assisted triage evaluates the information available at FNOL to identify factors such as severity, fraud risk, litigation potential, and subrogation opportunity, then routes the claim to the appropriate handling path.
Why it reduces FNOL time
Without automated routing, claims may sit in a general assignment queue while someone reviews the file and decides where it belongs. Triage logic can move straightforward claims toward fast-track or straight-through processing (STP) while directing higher-risk cases to experienced adjusters earlier.
How to put it in place
Start with clearly defined routing rules and use AI to support, not obscure, those decisions. Models should rely on explainable inputs, integrate with claims management workflows, and allow claims teams to override routing when new information changes the exposure.
Example
A low-severity glass claim with clear coverage and no injury indicators can move directly into a fast-track workflow, while a multi-vehicle accident with bodily injury indicators is routed immediately to a senior adjuster.
Watch out for
Poor data quality or weak model governance can create faster routing without better routing, so outputs need ongoing review against actual claim outcomes.
11: Automatic Vendor Dispatch
What it does
Automatic vendor dispatch connects the FNOL process directly with approved service providers so towing, glass repair, rental, or emergency mitigation can be initiated without waiting for a separate manual handoff.
Why it reduces FNOL time
The delay often comes after the claim is opened but before the first service action occurs. If an adjuster or contact-center employee has to review the file, identify a vendor, and send instructions manually, hours can be lost before assistance reaches the claimant.
How to put it in place
Define which loss types qualify for automatic dispatch, maintain approved vendor networks, and connect vendor availability and assignment data to the claims workflow. Claims teams should still be able to intervene when the loss is complex or the policyholder needs a different service option.
Example
After an auto collision leaves a vehicle undrivable, the FNOL workflow can dispatch an approved towing provider and initiate a rental referral as soon as the required claim checks are completed. The insured doesn’t have to wait for a separate adjuster handoff before those services begin.
12: AI-Assisted Coverage Checks at FNOL
What it does
Basic policy verification already confirms items such as whether the policy is active and whether the relevant coverage type exists. The emerging step is using AI to review policy wording, endorsements, deductibles, and authority limits to flag possible coverage issues during FNOL.
Why it reduces FNOL time
Coverage questions can delay assignment or early action when an adjuster has to search across policy documents before deciding how the claim should proceed. AI-assisted review can surface relevant provisions and potential conflicts earlier so the file reaches the right person with more context.
How to put it in place
Connect the claims workflow to authoritative policy documents and define which coverage questions AI can flag for review. Outputs should show the source wording behind each flag and route uncertain or complex cases to qualified claims staff rather than making autonomous coverage decisions.
Example
A commercial property loss is reported for damage involving a scheduled location and recent endorsement changes. The system surfaces the relevant endorsement language and deductible information for the adjuster before the first coverage review.
Watch out for
AI-driven coverage analysis still requires human review, clear authority controls, and careful governance.
Where MGAs Can Reduce FNOL Friction
MGAs with delegated claims authority often manage FNOL under carrier oversight while working with leaner teams, multiple carrier requirements, and bordereaux reporting obligations. That makes consistency at intake especially important.
Three approaches in this guide are particularly relevant. Partner and agent FNOL by API can reduce handoffs when brokers or distribution partners already hold the loss details. Generative AI voice agents can extend after-hours reporting capacity without requiring a full overnight intake team. AI-assisted coverage checks can also help surface carrier-specific policy wording, endorsements, and authority limits earlier in the process.
For MGAs, the biggest gains often come from capturing clean, consistent FNOL data up front, which reduces rework later in carrier reporting and bordereaux.
KPIs to Track Across the Three FNOL Cycles
Tracking FNOL performance by cycle makes it easier to identify where delay is actually occurring rather than relying on one end-to-end average.
| Cycle | KPI | What It Tells You |
|---|---|---|
| Reporting | Loss-to-report lag | How quickly losses reach the insurer |
| Reporting | % of claims reported digitally or by partners | Adoption of faster reporting channels |
| Intake | Average time to complete intake | How efficiently usable claim information is captured |
| Intake | Digital FNOL abandonment rate | How often claimants leave digital FNOL before completing it; track by step to see where |
| Response | FNOL-to-assignment time | How quickly claims move through triage and routing |
| Response | FNOL-to-first-contact time | How quickly the claimant hears from a person or receives a first service action, not just an automated acknowledgment |
These KPIs should also be segmented by line of business and loss type. Portfolio-wide averages can hide delays that affect specific claim categories, channels, or operating teams.
Faster FNOL Requires More Than Faster Intake
Reducing FNOL time means improving all three cycles, reporting, intake, and response not just the intake form.
The strongest FNOL programs remove avoidable waiting without sacrificing controls, data quality, or human judgment where it matters. That usually means fixing foundational gaps first, then applying automation and AI where they solve a specific operational delay.
Not sure where your gaps are? Book a free FNOL assessment with Practo Insura.

We specialize in developing innovative Property & Casualty (P&C) insurance software solutions, leveraging over 8 years of InsurTech expertise to simplify insurance operations and enhance efficiency.
Share Article via


Subscribe to our insights newsletter
Related Blog Posts
Top 9 Claims Estimator Solutions...
 23 Sep, 2026
Claims estimating can involve significant manual work, from reviewing damage...
Read More
7 Signs Your P&C Insurance...
14 Aug, 2026
For U.S. P&C insurers, AI is shifting from a technology...
Read More
Insurance Underwriting Automation: Implementation Guide...
12 Jun, 2026
Most P&C underwriters did not join the industry to chase...
Read More