Our Blog

How to Reduce FNOL Time in P&C Insurance: 12 Ways Across the 3 FNOL Cycles
 05 Oct, 2026
A homeowner discovers a burst pipe at 11 p.m. If the loss isn’t reported until the next morning, the insurer has already lost valuable time to initiate mitigation, assess exposure, and begin claim handling. During that gap, damage can continue to develop.
For claims organizations, reducing FNOL time is therefore not simply about improving intake efficiency. Earlier notification gives teams more opportunity to control claim severity, manage loss adjustment expense (LAE), identify potential coverage or recovery issues, and establish communication with the claimant sooner.
The impact of reporting lag is particularly visible in workers’ compensation. According to NCCI’s 2015 analysis, delays in reporting workplace injuries can increase claim costs by up to 51%. Claims reported more than two weeks late also showed greater attorney involvement and lower closure rates at 18 months.
Every FNOL moves through three cycles, and each one adds time. The 12 approaches in this guide address those cycles separately, from foundational practices to emerging capabilities.
Where FNOL Time Is Lost: The Three Operational Cycles
FNOL is often treated as a single intake event. A better way to look at it is as three consecutive time spans within the same claim. Each can add delay before the claims team is ready to act.
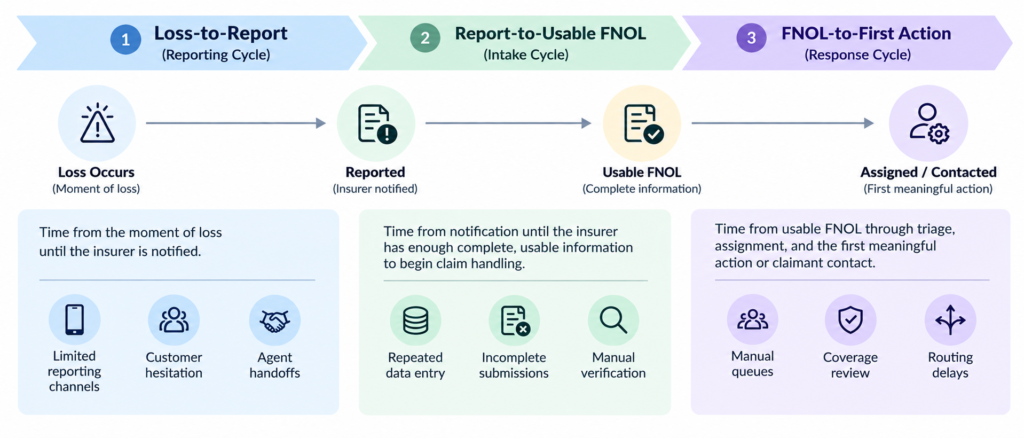
Cycle 1: Loss-to-Report
The reporting cycle begins at the moment of loss and ends when the insurer is notified. Delays can occur because of limited reporting channels, customer hesitation, agent handoffs, or a loss that happens outside normal business hours.
Cycle 2: Report-to-Usable FNOL
The intake cycle runs from notification until the insurer has enough complete, usable information to begin claim handling. Time is often lost through repeated data entry, incomplete submissions, unnecessary questions, document collection, or manual verification.
Cycle 3: FNOL-to-First Action
The response cycle begins once FNOL has been captured and continues through triage, assignment, and the first action or claimant contact. Manual queues, coverage review, routing decisions, and vendor coordination can extend this stage even when the initial report was submitted quickly.
Workers’ compensation data shows why these time gaps matter. An Integrated Benefits Institute analysis of 2.25 million workers’ compensation claims from 2010–2017 found that each additional day between injury and reporting was associated with about $50 more in total payments for medical-only claims. For indemnity claims, each additional day of reporting lag was associated with about $98 more in total payments.
We often see FNOL improvement efforts concentrate on intake because it’s the most visible stage. But delays can build before the claim reaches the insurer and again after the information has been captured.
12 Ways to Reduce FNOL Time Across the Three Claims Cycles
The following approaches address different sources of delay across reporting, intake, and response. Some are established capabilities, while others depend on newer data, automation, and AI-driven workflows.
Cycle 1: The Reporting Cycle
The reporting cycle is the first opportunity to reduce FNOL time because no downstream claims activity can begin until the loss reaches the insurer. According to J.D. Power’s 2026 U.S. Property Claims Satisfaction Study, only 38% of homeowners insurance customers reported FNOL digitally, showing that a large share of property claims still enter through channels that may involve more friction or manual handling.
The goal in this cycle is straightforward: make reporting available at the moment a loss occurs and reduce the number of handoffs between the policyholder, agent, partner, and claims system.
1: 24/7 Omnichannel Reporting
What it does
24/7 omnichannel reporting lets policyholders report a loss through web, mobile, SMS, phone, or chat without waiting for business hours or moving between disconnected channels.
Why it reduces FNOL time
It removes a basic source of delay: access. A claimant who can start FNOL immediately is less likely to wait for an agent or contact center to become available. According to J.D. Power’s 2025 U.S. Auto Claims Satisfaction Study, 26% of auto customers had deductibles of $1,000 or more, while 7% had avoided filing a claim because of concerns about a rate increase. Easier reporting won’t remove that hesitation, but it can reduce friction once a customer decides to file.
How to put it in place
Connect every reporting channel to the same claims workflow and data rules so each submission creates one consistent claim record.
Example
A restaurant owner discovers a break-in early Sunday morning. Rather than waiting for a commercial lines contact to reopen on Monday, the insured can report the loss digitally, provide the basic details, and receive a claim number immediately.
2: Partner and Agent FNOL by API
What it does
Partner and agent FNOL by API allows brokers, agents, body shops, mitigation providers, and other approved partners to submit loss information directly into the claims environment instead of sending details by email or calling a claims team.
Why it reduces FNOL time
The main benefit is fewer handoffs. When a partner already has the loss details, requiring them to pass that information to a separate intake team creates avoidable delay and increases the chance of incomplete or duplicated data. Direct submission moves the claim into the FNOL process as soon as the partner captures the required information.
How to put it in place
Define a minimum data set for each partner type, then connect partner portals or systems to the claims platform through secure APIs. Validation rules should check required fields, policy references, duplicate claims, and submission permissions before the record enters the claims workflow.
Example
After a commercial property water loss, an approved mitigation vendor can submit the initial loss details, property information, and emergency service request directly from its system. The claim enters triage without waiting for a separate email to be reviewed and manually re-entered.
3: Event-Driven FNOL
What it does
Event-driven FNOL uses connected data sources such as vehicle telematics and smart-home sensors to detect a potential loss and automatically trigger, prefill, or prompt the reporting process.
Why it reduces FNOL time
This approach shortens the reporting cycle by reducing dependence on the policyholder to initiate contact. A crash signal, water-leak alert, freeze warning, or fire-related sensor event can create an immediate notification path, giving the insurer an earlier opportunity to confirm the loss and begin the appropriate claims workflow.
How to put it in place
Insurers need reliable event data, policy matching logic, consent controls, and rules that determine when an event should create a claim, open a draft FNOL, or simply prompt the insured to respond. Thresholds should be calibrated carefully so routine events don’t generate unnecessary claims activity.
Example
A connected vehicle detects a significant collision and transmits an event signal within seconds. The system can match the vehicle to the policy, pre-populate available information, and prompt the driver to confirm the loss rather than relying on a later phone call to start FNOL.
Watch out for
This technology is already in production at some large US carriers, but adoption across the broader P&C market remains early.
4: Proactive Catastrophe Outreach
What it does
Proactive catastrophe outreach uses storm-path, hail, wind, and other event data to identify policyholders who may have been affected and contact them before they initiate a claim.
Why it reduces FNOL time
During catastrophe events, reporting delays often increase because contact centers become overloaded and policyholders may not know what information they need to provide. Targeted outreach can shorten that gap by prompting likely affected customers to confirm damage through a digital FNOL path rather than waiting for them to find the correct reporting channel.
How to put it in place
Insurers need reliable catastrophe data, geocoded policy information, and rules for determining which policyholders should receive outreach. Messages should direct customers to a simple reporting flow and make it clear that outreach identifies possible exposure rather than assuming a covered loss has occurred.
Example
After a severe hailstorm crosses a defined area, homeowners with insured properties in the affected zone receive a message asking whether they sustained damage. Customers who confirm a loss can begin FNOL immediately through a prefilled digital flow.
Cycle 2: The Intake Cycle
Once a loss reaches the insurer, the next task is turning the report into information claims teams can use. The aim isn’t to collect everything immediately. It’s to capture the right information at the right point so the claim can move forward without unnecessary intake work.
5: Prefill from Policy Data
What it does
Policy-data prefill automatically brings existing insured, policy, vehicle, property, and coverage information into the FNOL process rather than asking the claimant or adjuster to enter it again.
Why it reduces FNOL time
Re-entering information the insurer already holds adds time without improving the claim record. Prefill allows the claimant to confirm or correct existing details and spend more time providing information that is specific to the loss.
How to put it in place
Connect the FNOL workflow with the policy administration system and define which fields can be safely pre-populated, while keeping a clear way to update information that has changed.
Example
A driver reporting a parking-lot collision opens FNOL and finds the policy number, insured details, covered vehicle, and contact information already populated. The driver confirms those details and moves directly to describing the accident and damage.
6: Dynamic, Loss-Specific Questionnaires
What it does
Dynamic questionnaires change the FNOL questions based on the type of loss and the answers already provided. A windshield claim, theft loss, workplace injury, and multi-vehicle accident shouldn’t follow the same intake path.
Why it reduces FNOL time
Static forms often collect information that has little relevance to the loss while failing to ask the questions claims teams actually need. Branching logic removes unnecessary fields and surfaces follow-up questions only when a previous answer makes them relevant.
How to put it in place
Start with the minimum information required across all claims, then build question sets by line of business and loss type. Claims teams should help define the branching rules so the questionnaire reflects actual triage and assignment needs rather than becoming a longer digital form.
Example
For a workers’ compensation claim involving a lifting injury, the intake can ask about the employee’s role, injury location, treatment received, and work status. It doesn’t need to display questions designed for auto damage, third-party vehicles, or property repairs.
7: Minimum Viable FNOL
What it does
Minimum viable FNOL captures only the information required to establish the claim and move it into triage. Photos, police reports, repair estimates, witness statements, and other supporting material can follow after the claim is opened.
Why it reduces FNOL time
In our experience, intake processes are often treated as if the claim record must be complete before anyone can act. That creates delay inside the intake itself. For many losses, teams need only enough information to identify the policy, understand what happened, locate the loss, contact the claimant, and make an initial routing decision.
The remaining information can be gathered through later digital requests, adjuster follow-up, partner integrations, or third-party data. This separates claim creation from claim enrichment and allows triage and assignment to begin sooner.
How to put it in place
Define the minimum data needed to open and route a claim by line of business, then identify what can safely be collected later. Complex injury, fraud, or coverage-sensitive claims should still trigger additional upfront requirements.
Example
After a fleet vehicle accident, the insured may not yet have complete driver statements, repair estimates, or third-party documentation. The claim can still be opened with the policy, vehicle, driver, date and location of loss, known damage, and contact details while the remaining information is collected later.
Watch out for
A faster intake still needs enough information for basic fraud screening and an initial reserve; minimum viable FNOL should remove unnecessary upfront work, not essential controls.
8: Generative AI Voice Agents for FNOL
What it does
AI voice and chat support agents can handle natural phone conversations for straightforward FNOL interactions, especially after hours. For more complex calls, they can transcribe the conversation and structure key claim details for a human reviewer.
Why it reduces FNOL time
Conversational voice AI can collect initial loss information as the call happens instead of placing the claimant in a queue or requiring a callback. Unlike older IVR or scripted chatbot flows, newer systems can interpret more natural descriptions and ask follow-up questions based on the conversation.
How to put it in place
Start with well-defined, lower-complexity claim types and clear escalation rules. The system should write structured data into the FNOL workflow, preserve the call record, and transfer the claimant to a person when injury, distress, coverage uncertainty, or unusual circumstances require judgment.
Example
A homeowner calling after hours about a minor kitchen fire can describe what happened conversationally. The voice agent captures the loss location, reported damage, emergency response, and contact details, then prepares the claim for review.
Cycle 3: The Response Cycle
Once the FNOL is usable, speed depends on how quickly the claim moves into triage, assignment, and action. McKinsey has identified the potential for claims transformation to reduce loss adjustment expenses by 25–30% and indemnity spend by 3–5 percentage points. That’s a reminder of what’s at stake when early claims work still depends heavily on manual steps.
The focus here is to remove avoidable queues between intake and the first claims decision, contact, or service action.
9: Instant Acknowledgment and Proactive Status Updates
What it does
Instant acknowledgment confirms that the claim has been received, provides a claim number and next steps, and keeps the claimant informed as the claim progresses.
Why it reduces FNOL time
Acknowledgment doesn’t shorten the reporting event itself, but it reduces the gap between submission and the claimant’s first confirmation that the process has started. Proactive updates also reduce inbound status calls that can consume adjuster capacity during early claim handling.
J.D. Power’s 2026 U.S. Property Claims Satisfaction Study found that 45% of customers received claim updates digitally, indicating that digital communication is already an important part of the claims experience.
How to put it in place
Trigger acknowledgments directly from claim creation and connect later updates to real workflow events such as assignment, document requests, inspections, or vendor appointments. Because prompt-acknowledgment requirements vary by state, automated communication should support jurisdiction-specific compliance controls.
Example
An employer reports a warehouse injury online and immediately receives a claim number, next steps for submitting the medical provider’s details, and confirmation when a claims professional is assigned.
10: AI Triage at FNOL with Automated Routing
What it does
AI-assisted triage evaluates the information available at FNOL to identify factors such as severity, fraud risk, litigation potential, and subrogation opportunity, then routes the claim to the appropriate handling path.
Why it reduces FNOL time
Without automated routing, claims may sit in a general assignment queue while someone reviews the file and decides where it belongs. Triage logic can move straightforward claims toward fast-track or straight-through processing (STP) while directing higher-risk cases to experienced adjusters earlier.
How to put it in place
Start with clearly defined routing rules and use AI to support, not obscure, those decisions. Models should rely on explainable inputs, integrate with claims management workflows, and allow claims teams to override routing when new information changes the exposure.
Example
A low-severity glass claim with clear coverage and no injury indicators can move directly into a fast-track workflow, while a multi-vehicle accident with bodily injury indicators is routed immediately to a senior adjuster.
Watch out for
Poor data quality or weak model governance can create faster routing without better routing, so outputs need ongoing review against actual claim outcomes.
11: Automatic Vendor Dispatch
What it does
Automatic vendor dispatch connects the FNOL process directly with approved service providers so towing, glass repair, rental, or emergency mitigation can be initiated without waiting for a separate manual handoff.
Why it reduces FNOL time
The delay often comes after the claim is opened but before the first service action occurs. If an adjuster or contact-center employee has to review the file, identify a vendor, and send instructions manually, hours can be lost before assistance reaches the claimant.
How to put it in place
Define which loss types qualify for automatic dispatch, maintain approved vendor networks, and connect vendor availability and assignment data to the claims workflow. Claims teams should still be able to intervene when the loss is complex or the policyholder needs a different service option.
Example
After an auto collision leaves a vehicle undrivable, the FNOL workflow can dispatch an approved towing provider and initiate a rental referral as soon as the required claim checks are completed. The insured doesn’t have to wait for a separate adjuster handoff before those services begin.
12: AI-Assisted Coverage Checks at FNOL
What it does
Basic policy verification already confirms items such as whether the policy is active and whether the relevant coverage type exists. The emerging step is using AI to review policy wording, endorsements, deductibles, and authority limits to flag possible coverage issues during FNOL.
Why it reduces FNOL time
Coverage questions can delay assignment or early action when an adjuster has to search across policy documents before deciding how the claim should proceed. AI-assisted review can surface relevant provisions and potential conflicts earlier so the file reaches the right person with more context.
How to put it in place
Connect the claims workflow to authoritative policy documents and define which coverage questions AI can flag for review. Outputs should show the source wording behind each flag and route uncertain or complex cases to qualified claims staff rather than making autonomous coverage decisions.
Example
A commercial property loss is reported for damage involving a scheduled location and recent endorsement changes. The system surfaces the relevant endorsement language and deductible information for the adjuster before the first coverage review.
Watch out for
AI-driven coverage analysis still requires human review, clear authority controls, and careful governance.
Where MGAs Can Reduce FNOL Friction
MGAs with delegated claims authority often manage FNOL under carrier oversight while working with leaner teams, multiple carrier requirements, and bordereaux reporting obligations. That makes consistency at intake especially important.
Three approaches in this guide are particularly relevant. Partner and agent FNOL by API can reduce handoffs when brokers or distribution partners already hold the loss details. Generative AI voice agents can extend after-hours reporting capacity without requiring a full overnight intake team. AI-assisted coverage checks can also help surface carrier-specific policy wording, endorsements, and authority limits earlier in the process.
For MGAs, the biggest gains often come from capturing clean, consistent FNOL data up front, which reduces rework later in carrier reporting and bordereaux.
KPIs to Track Across the Three FNOL Cycles
Tracking FNOL performance by cycle makes it easier to identify where delay is actually occurring rather than relying on one end-to-end average.
| Cycle | KPI | What It Tells You |
|---|---|---|
| Reporting | Loss-to-report lag | How quickly losses reach the insurer |
| Reporting | % of claims reported digitally or by partners | Adoption of faster reporting channels |
| Intake | Average time to complete intake | How efficiently usable claim information is captured |
| Intake | Digital FNOL abandonment rate | How often claimants leave digital FNOL before completing it; track by step to see where |
| Response | FNOL-to-assignment time | How quickly claims move through triage and routing |
| Response | FNOL-to-first-contact time | How quickly the claimant hears from a person or receives a first service action, not just an automated acknowledgment |
These KPIs should also be segmented by line of business and loss type. Portfolio-wide averages can hide delays that affect specific claim categories, channels, or operating teams.
Faster FNOL Requires More Than Faster Intake
Reducing FNOL time means improving all three cycles, reporting, intake, and response not just the intake form.
The strongest FNOL programs remove avoidable waiting without sacrificing controls, data quality, or human judgment where it matters. That usually means fixing foundational gaps first, then applying automation and AI where they solve a specific operational delay.
Not sure where your gaps are? Book a free FNOL assessment with Practo Insura.

Top 9 Claims Estimator Solutions for P&C Insurance in USA
23 Sep, 2026
Claims estimating can involve significant manual work, from reviewing damage photos and identifying repair needs to checking costs and preparing an estimate. As claim volumes grow, these steps can slow the process and increase pressure on claims teams.
Claims estimator technology helps automate parts of this work by analyzing claim data, images and pricing information to support damage assessment, repair scoping and estimate creation.
For P&C insurers, the market now includes established platforms such as CCC, Xactimate and Mitchell, as well as newer AI tools that support photo-based assessments, remote inspections and integration with existing claims systems.
Not all of these solutions work in the same way. Some generate detailed estimates, while others provide damage assessments or initial scopes for adjuster review.
In this guide, we compare nine claims estimator solutions across auto and property insurance, including their capabilities, integrations and level of human involvement.
Quick Comparison of Claims Estimator Solutions
The solutions below differ in the claims they support, how they are deployed and how much of the estimating process they handle.
| Solution | Claims Type | Main Capability | Deployment | Human Involvement |
|---|---|---|---|---|
| CCC Intelligent Solutions | Auto | AI-assisted line-item estimating and straight-through estimating for eligible claims | CCC platform | Smart Estimate supports appraiser review; Estimate-STP can automate eligible claims |
| Practo Insura | Auto & Property | AI-assisted damage assessment and estimated claim information | Platform / Integration | Adjuster reviews and can revise estimates |
| Mitchell / Enlyte | Auto | AI-assisted component identification and line-item estimating | Cloud estimating platform | Appraisers can review, complete and approve estimates |
| Tractable | Auto & Property | Computer vision damage assessment and estimate support | API / Web integration layer | Depends on carrier workflow and level of automation |
| Ravin AI | Auto | Remote vehicle inspection, damage assessment and repair-cost calculation | API / Mobile / Web | Depends on insurer workflow |
| Hosta AI | Property | Remote interior assessment, measurements, scoping and estimating support | API / Assessment platform | Depends on how outputs are used within the estimating workflow |
| Verisk Xactimate | Property | Line-item property estimating with localized pricing and AI assistance | Desktop / Online / Mobile | Users can review, edit or override AI recommendations |
| Cotality Claims Estimate | Property | Property estimating, LiDAR scoping and AI-assisted voice-to-line-item input | Desktop / Mobile | Adjuster-led with AI and automated validation support |
| Solera Qapter / Audatex | Auto | AI-assisted damage detection, line-item estimating and total-loss support | Modular cloud platform | Supports automated workflows with appraiser review where required |
3 Platform-Native Claims Estimating Solutions
These solutions provide estimating as part of a broader claims platform, allowing insurers to connect damage assessment, estimate creation and other claims activities within the same environment.
1. CCC Intelligent Solutions
CCC Intelligent Solutions is widely used across the U.S. auto claims ecosystem, connecting insurers with repair facilities, parts suppliers and other participants involved in the claims process.
For estimating, CCC offers Smart Estimate and Estimate-STP, which support different levels of automation. Smart Estimate applies CCC’s estimating logic and AI to collision photos to identify likely repair requirements and recommend estimate lines. It is designed to guide appraisers through the estimating process, while insurers can configure estimating parameters and business rules around their own requirements.
Estimate-STP extends automation further by allowing eligible claims to move through a straight-through estimating workflow. Carriers can define rules and eligibility thresholds that determine which claims can be handled automatically and which require adjuster review.
Because these capabilities operate within CCC’s broader auto claims environment, estimating can connect with other activities such as repair facility assignment, parts sourcing and total-loss handling.
Key Strengths
- Strong presence across the U.S. auto claims ecosystem
- Supports both AI-assisted and straight-through estimating workflows
- Allows insurers to configure business rules and claim eligibility criteria
- Connects estimating with other auto claims processes
Considerations
- Focused primarily on auto physical damage
- Smart Estimate supports appraisers rather than operating as a fully touchless estimating process
- Straight-through processing depends on carrier-defined rules and claim eligibility
Claims supported: Auto physical damage
Input: Collision photos, VIN and claim data
Output: Repair requirements and line-level estimate recommendations
Deployment: CCC platform
Human involvement: Smart Estimate supports appraiser review, while eligible claims can use Estimate-STP for straight-through processing
Best suited for: U.S. auto insurers looking to combine AI-assisted estimating with configurable automation within a broader claims ecosystem
2. Practo Insura
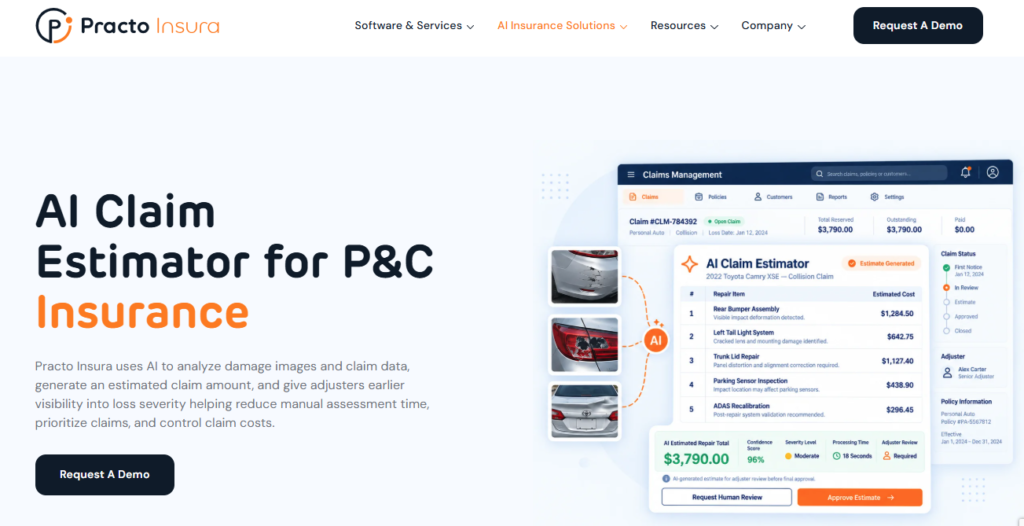
Practo Insura provides AI-assisted claims estimation for P&C insurers across both auto and property claims, giving carriers more flexibility than solutions focused on a single line of business. It can be used within Practo Insura’s claims platform or integrated into an insurer’s existing core environment, making it suitable for carriers that want to add AI without necessarily replacing their current claims system.
The estimator analyzes damage images and claim data to identify affected components, reference repair or replacement costs, and generate an estimated claim amount with an AI-generated damage summary. Rather than treating the estimate as a final automated decision, the system gives adjusters a structured starting point that they can review and refine.
Adjusters can revise estimates before the claim progresses, while estimate versioning keeps a record of previous and updated amounts, dates and user changes. This helps combine faster AI-assisted estimation with the control and traceability claims teams still need.
Key Strengths
- Supports both auto and property claims
- Can work within Practo Insura Claims or alongside an existing core system
- Keeps adjusters in control of final estimate review
- Supports estimate version history and auditability
- Can be configured around carrier-specific claims workflows rather than forcing a fixed process
Considerations
- Implementation is tailored to insurer requirements rather than provided as a fixed off-the-shelf package
- Integration scope depends on the carrier’s existing systems and workflow requirements
Claims supported: Auto and property
Input: Damage images and claim data
Output: Estimated claim amount and AI-generated damage summary
Deployment: Practo Insura platform or integration with an existing core system
Human involvement: Adjuster reviews and can revise the estimate before the claim moves forward
Best suited for: P&C carriers, MGAs and specialty insurers that want AI-assisted estimation with greater workflow flexibility and adjuster control
3. Enlyte / Mitchell
Mitchell, part of Enlyte, provides auto physical damage estimating technology for insurers and repair organizations. Its broader estimating environment includes Mitchell Cloud Estimating, while its AI-assisted estimating capability is branded Mitchell Intelligent Estimating.
At the core of the AI workflow is Mitchell Intelligent Damage Analysis, which uses computer vision to evaluate vehicle damage images, identify affected components and recommend repair operations. These recommendations can then be mapped to individual estimate lines and incorporated into the estimating process.
One of Mitchell’s strongest differentiators is its open architecture. Carriers can use Mitchell’s own AI capabilities or connect third-party computer vision providers, giving insurers more flexibility in how they build their estimating workflow. Estimate data can also be exchanged using CIECA BMS standards, helping support interoperability with other claims systems.
Key Strengths
- Strong focus on auto physical damage estimating
- AI recommendations can support line-item estimate creation
- Open architecture allows third-party AI integration
- Supports CIECA BMS data exchange
- Gives carriers flexibility in how AI is incorporated into their estimating workflow
Considerations
- Primarily focused on auto rather than property claims
- Workflow complexity may increase when multiple third-party AI tools are integrated
- The final level of automation depends on carrier configuration and connected technologies
Claims supported: Auto physical damage
Input: Vehicle damage photos and claim information
Output: Component-level repair recommendations and estimate lines
Deployment: Cloud-based estimating platform
Human involvement: Appraisers can review, complete and approve AI-assisted estimates
Best suited for: Auto insurers that want an established estimating platform with flexibility to integrate their preferred AI technologies
3 Standalone AI Claims Assessment Solutions
These tools focus on AI-driven damage analysis, remote inspection or image-based assessment and typically feed their outputs into an insurer’s existing claims or estimating system.
4. Tractable
Tractable uses computer vision to analyze damage images across both auto and property claims. Rather than functioning only as a standalone estimating platform, it is designed to work as an AI layer that can support and enhance an insurer’s existing claims and estimating environment.
Its technology can support several stages of the claims process, including FNOL triage, damage assessment, estimate pre-population, and estimate review. For auto claims, Tractable can analyze collision photos and help generate a partial or complete estimate that can flow into an established estimating workflow.
On the property side, policyholders can submit damage photos through a web-based experience. Tractable’s AI can identify, classify and measure damage, with the resulting information used to support estimate generation within systems such as Xactimate.
A major strength is its integration model. Tractable works with established platforms including Mitchell for auto and Verisk Xactimate for property, allowing insurers to introduce AI-driven image analysis without replacing their existing estimating systems.
Key Strengths
- Supports both auto and property claims
- Strong focus on computer vision and image-based damage assessment
- Can support estimate pre-population and review
- Integrates with established estimating platforms such as Mitchell and Xactimate
- Allows insurers to add AI capabilities without replacing their current estimating environment
Considerations
- Often works alongside another estimating platform rather than replacing it
- Final estimating workflow depends on the carrier’s existing systems and integrations
- Level of automation varies depending on implementation and claim type
Claims supported: Auto and property
Input: Damage photos submitted by policyholders, repair facilities or adjusters
Output: Damage assessment, estimate inputs, repair recommendations and review support
Deployment: API and web-based integration layer
Human involvement: Depends on carrier workflow and level of automation
Best suited for: Insurers that want to add AI-powered image analysis and estimation support while retaining their existing estimating platforms
5. Ravin AI
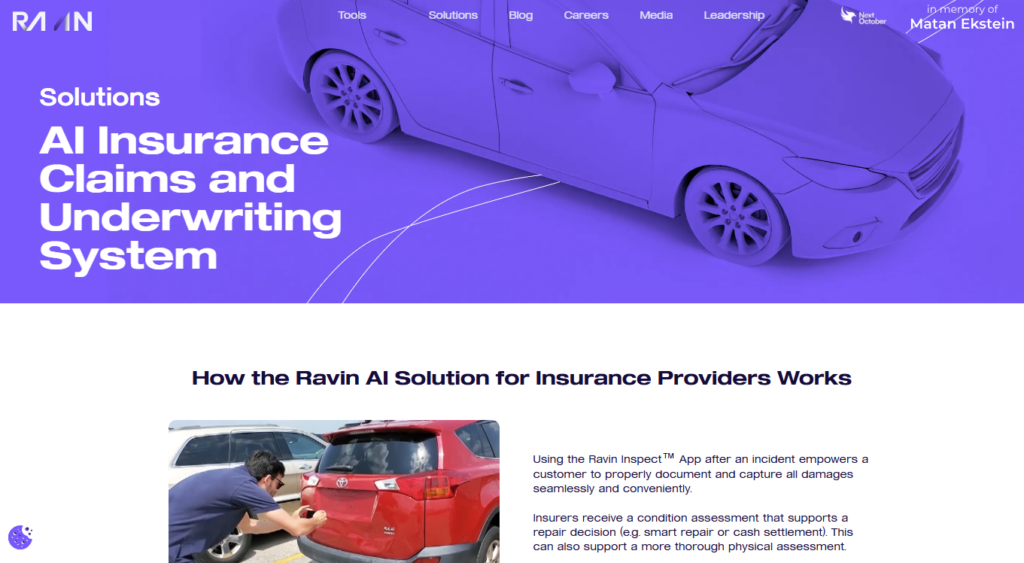
Ravin AI focuses on vehicle inspection and damage assessment for auto claims, using computer vision to analyze photos and video captured from claimants, tow operators or other users in the field.
Its workflow starts with guided image capture. RAVIN Inspect allows users to submit vehicle photos or video from a mobile device without installing a dedicated app, while RAVIN Eye supports damage review, repair-versus-total-loss triage and repair cost calculation.
The results can then be passed into the insurer’s existing claims environment through APIs. This makes Ravin particularly relevant for carriers that want to improve remote vehicle inspection and early claims triage without replacing their broader claims management system.
Key Strengths
- Combines guided vehicle capture with AI-based damage assessment
- Supports photo and video submission without requiring a dedicated app
- Can support repair cost calculation and total-loss triage
- API-based architecture supports integration with existing claims systems
- Useful for remote inspection and early-stage claims handling
Considerations
- Focused on auto claims rather than property
- Estimating is closely linked to vehicle inspection and capture workflows
- Final use of the AI output depends on the insurer’s claims process and integration setup
Claims supported: Auto
Input: Guided mobile photos and video
Output: Damage assessment, repair cost calculation, triage and total-loss recommendation
Deployment: API with mobile/web capture tools
Human involvement: Depends on the insurer’s claims workflow
Best suited for: Auto insurers and mobility businesses looking to combine remote vehicle inspection with AI-supported claims assessment
6. Hosta AI
Hosta AI focuses on property claims, particularly interior damage assessment and remote property documentation. Policyholders or field users can capture a small set of room images, which Hosta analyzes to generate measurements, material details, damage information and structured property data.
The platform can produce floor plans, 3D measurements, elevations and Xactimate Sketch output. Hosta has also positioned its technology as capable of supporting completed estimates, rather than only providing preliminary scoping information.
This makes Hosta useful for insurers looking to reduce reliance on physical interior inspections while still feeding structured data into established estimating workflows. Its integrations are not limited to Xactimate alone, with support also extending into other claims and estimating environments.
Key Strengths
- Built specifically for interior property claims
- Can reduce the need for on-site property inspections
- Generates measurements, floor plans, elevations and 3D property data
- Supports Xactimate Sketch generation
- Can contribute to completed estimating workflows, not only preliminary scoping
- Designed to integrate with established claims and estimating systems
Considerations
- Focused primarily on property rather than auto claims
- The final workflow depends on the estimating platform and carrier implementation
- Insurers should evaluate how Hosta’s generated estimate or assessment data fits into their existing review process
Claims supported: Property
Input: Interior property photos
Output: Damage assessment, measurements, floor plans, elevations, 3D data, Xactimate Sketch and estimating information
Deployment: API / assessment platform
Human involvement: Depends on how the insurer incorporates Hosta output into its estimating and review workflow
Best suited for: Property insurers looking to automate interior assessment, reduce site visits and feed structured property data into established estimating systems
3 Established Claims Estimating Systems
These are mature estimating platforms built around repair, construction or pricing data, with newer AI and automation capabilities being added to support existing estimating workflows.
7. Verisk Xactimate
Verisk Xactimate is one of the most established property claims estimating platforms in the U.S. and Canada. It is built around localized pricing data for materials, labor and repair activities, helping adjusters create detailed line-item estimates based on the scope and location of a loss.
The platform works across desktop, online and mobile environments and connects with XactAnalysis for assignment, estimate exchange and broader claims workflow management. Verisk researches pricing across more than 460 localized markets in the U.S. and Canada, giving estimators location-specific cost information when building property estimates.
Verisk has also expanded its AI capabilities through XactAI. These features can support line-item recommendations, automatic photo labeling and descriptions, note summarization and floor plan capture through Sketch Scan. AI-generated output is still designed to support human decision-making, with users able to review, edit or override recommendations.
Key Strengths
- Established property claims estimating ecosystem
- Detailed line-item estimates supported by localized pricing data
- Pricing research across more than 460 U.S. and Canadian markets
- AI can support line-item recommendations, documentation and floor plan capture
- Broad integration ecosystem through XactAnalysis and third-party technologies
- Human review remains part of the estimating process
Considerations
- Focused mainly on property rather than auto claims
- Works best within the wider Xactimate and XactAnalysis ecosystem
- AI capabilities assist the estimating process rather than replacing adjuster judgment
Claims supported: Property
Input: Adjuster scope, photos, sketches, floor plan data and other property information
Output: Detailed line-item property estimate
Deployment: Desktop, online and mobile
Human involvement: Users can review, edit or override AI-generated recommendations
Best suited for: Property insurers, adjusting firms and restoration organizations that need detailed estimating supported by localized pricing data and an established claims ecosystem
8. Cotality Claims Estimate
Cotality Claims Estimate, formerly known as Symbility Mobile Claims under CoreLogic, is a property estimating platform built for both field and desk-based claims workflows. It combines structured estimating tools with construction pricing data to help claims teams create detailed property repair estimates.
The platform supports guided estimating, photo capture, diagramming and LiDAR-based room scanning on supported iOS devices. Cotality also promotes an AI-powered voice engine that can convert spoken descriptions of property damage into estimate line items, helping adjusters capture information more quickly while working in the field.
Claims Estimate sits within Cotality’s broader property claims environment, alongside tools for inspection, scoping, workflow management and estimate validation. This allows insurers to connect estimating with other parts of the property claims process rather than treating it as a separate activity.
Key Strengths
- Built specifically for property claims estimating
- Supports both desktop and mobile workflows
- Includes LiDAR-based room scanning for field scoping
- AI-powered voice input can help convert spoken damage descriptions into line items
- Uses construction pricing data to support detailed estimates
- Connects with a broader suite of property claims tools
Considerations
- Focused on property rather than auto claims
- The estimating workflow remains adjuster-led even with newer AI assistance
- Insurers should evaluate how the broader Cotality claims suite fits with their existing systems
Claims supported: Property
Input: Adjuster scope, photos, diagrams, LiDAR scans and voice input
Output: Detailed line-item property estimate
Deployment: Desktop and mobile
Human involvement: Adjuster-led, with AI and automated validation supporting the estimating process
Best suited for: Property insurers and adjusting firms looking for mobile-first estimating, field scoping tools and AI-assisted workflow support
9. Solera Qapter / Audatex
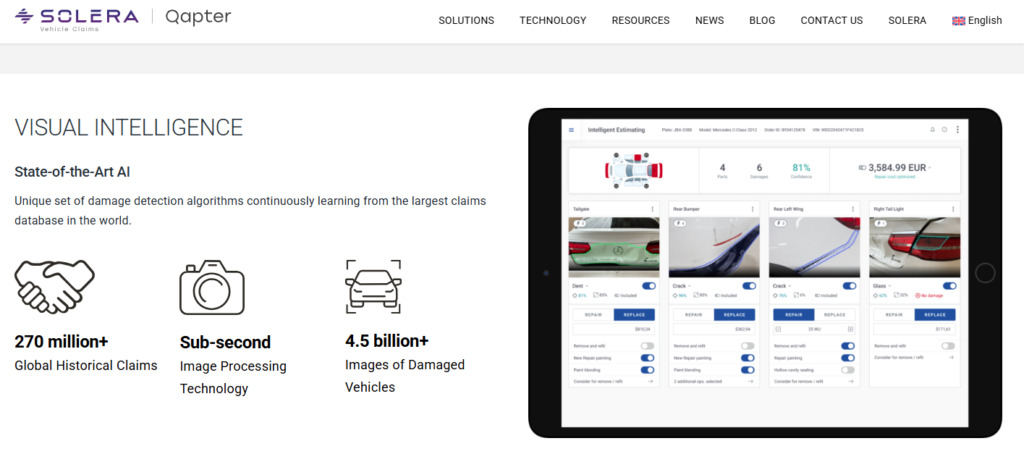
Solera Qapter is an AI-assisted auto claims estimating solution designed to support the process from damage capture through estimating and settlement. It uses image analysis to identify damaged vehicle parts, assess damage severity and recommend repair operations that can be translated into line-item estimates.
The platform combines AI with Solera’s vehicle and repair data to support repair planning, estimating, triage and total-loss workflows. Solera positions the AI as a tool that complements human expertise, allowing appraisers or claims teams to review and adjust estimates when required.
Qapter is offered as a modular cloud-based suite, so insurers can use individual capabilities or combine them into a broader auto claims workflow. Solera has also expanded the platform with Qapter Direct Dispatch, which adds AI-assisted damage estimating and automated vehicle equipment identification to help move claims more efficiently from intake into the estimating process.
Key Strengths
- Strong focus on auto physical damage estimating
- Uses AI for damage detection, parts identification and repair recommendations
- Supports line-item estimates, triage and total-loss workflows
- Modular architecture allows insurers to select specific capabilities
- Qapter Direct Dispatch adds AI-assisted estimating earlier in the claims process
- Supports workflows where human appraisers can review and adjust AI-generated estimates
Considerations
- Focused on auto rather than property claims
- The level of automation depends on the modules and workflow used
- Human review may still be required depending on carrier requirements
Claims supported: Auto physical damage
Input: Vehicle damage photos, VIN and claim data
Output: Damage assessment, repair operations, line-item estimate and total-loss support
Deployment: Modular cloud platform
Human involvement: AI can support automated workflows, with appraiser review available where required
Best suited for: Auto insurers looking for AI-assisted estimating within a modular claims workflow that can support both automation and human review
How Claims Estimation Solutions Differ
Claims estimator solutions do not all play the same role in the claims process. Some are built directly into broader claims platforms, others work as AI layers that support an existing estimating system, and some are long-established estimating tools that are gradually adding more automation.
Platform-Native Estimating
Solutions such as CCC, Practo Insura and Mitchell place estimating within a broader claims environment. This can help insurers connect damage assessment and estimate creation with other workflows such as claim handling, repair management, total-loss processing or adjuster review.
Standalone AI Assessment
Tools such as Tractable, Ravin AI and Hosta AI focus more heavily on image analysis, remote inspection and damage assessment. They are often used alongside an insurer’s existing claims or estimating platform rather than replacing it completely.
Established Estimating Systems
Platforms such as Verisk Xactimate, Cotality Claims Estimate and Solera Qapter are built around established estimating workflows, pricing data and repair or construction information. AI and automation are increasingly being added to these systems to support faster scoping, line-item recommendations and more efficient estimate preparation.
For insurers, the main question is therefore not only which vendor offers the most features, but which type of estimating model fits the existing claims environment, line of business and desired level of automation.
Conclusion
Claims estimation technology now covers a wide range of approaches, from established estimating platforms to AI-driven assessment tools and more configurable claims systems.
For insurers, the right choice depends on more than the amount of AI a platform uses. The more important questions are whether the solution supports the right line of business, fits the existing claims environment, produces the type of estimate or assessment required, and gives claims teams the appropriate level of human oversight.
Auto carriers may prioritize vehicle damage analysis, repair estimating and total-loss workflows, while property insurers may place more emphasis on scoping, measurements, construction pricing and remote inspections. Some insurers may need a complete estimating platform, while others may be better served by adding an AI layer to systems they already use.
For carriers looking for a more configurable approach across auto and property claims, Practo Insura provides AI-assisted claims estimation that can be built around existing workflows and integrated with the broader claims environment.
7 Signs Your P&C Insurance Company Is Ready for AI Automation
14 Aug, 2026
For U.S. P&C insurers, AI is shifting from a technology experiment to a consideration in day-to-day operations. Carriers and MGAs are evaluating how it can help them handle growing workloads, improve operational efficiency, and make better use of existing resources. But adopting AI is not simply a matter of selecting a solution and putting it into production.
The more important question is whether the organization is ready to use AI effectively.
An insurer may have processes that appear well suited to automation but lack the data, integration capabilities, or operational foundation needed to support it. Another may have the right technology environment but no clearly defined business problem or measurable outcome to justify an AI initiative.
That makes readiness an important part of the decision. Before evaluating solutions, insurance leaders need to understand whether their current processes, teams, technology, and business priorities create a practical foundation for AI automation.
Here are seven signs that your P&C insurance company may be ready to take the next step.
1. Your Teams Are Spending Too Much Time on Repetitive Work
P&C insurance operations involve a steady stream of routine activities, from collecting information and reviewing documents to updating records and moving data between systems. These tasks are necessary, but they don't always require the full attention of experienced insurance professionals.
The issue becomes more significant when routine work starts taking up a substantial share of team capacity. Employees have less time for work that requires judgment and expertise, while growing volumes put additional pressure on the same teams.
Look for signs such as:
- Employees repeatedly performing the same steps across large volumes of work.
- Skilled staff spending significant time gathering, checking, or transferring information.
- Teams adding capacity primarily to keep up with routine operational workload.
AI automation can address parts of this problem by taking on defined, repeatable tasks within an existing workflow. Depending on the process, this could include extracting information from documents, organizing incoming data, or routing information to the appropriate next step. Employees remain responsible for decisions and exceptions that require professional judgment.
When routine work is consuming more employee capacity without adding corresponding business value, it may be one of the clearest areas to evaluate for AI automation.
Related Read: 9 Customer Support Workflows Every P&C Insurer Should Automate
2. Your Operational Workload Is Growing Faster Than Your Team
A P&C insurer can have efficient processes and still run into a capacity problem when business volume grows faster than the team supporting it. More policies, submissions, claims, or service requests can quickly increase the amount of operational work that needs to be handled.
The warning sign is not simply that employees are busy. It's when growth consistently requires additional manual capacity to maintain the same level of service.
The warning signs usually appear when:
- Processing backlogs increase as business volume rises.
- Teams need additional resources primarily to handle higher transaction volumes.
- Service levels become harder to maintain during periods of increased demand.
- Operational capacity becomes a constraint on taking on more business.
AI automation can give insurers another way to scale capacity. Instead of treating every increase in volume as a need for proportional increases in manual effort, carriers and MGAs can identify workflows where AI can handle defined tasks or support employees.
This creates a more scalable operating model: business volume can grow without every increase automatically translating into more manual workload.
3. Manual Handoffs Are Slowing Down Your Workflows
P&C insurance workflows often span multiple teams, applications, and stages. Information may need to move from one person or system to another before a task can progress. When those transitions depend on manual intervention, even a straightforward process can take longer than it should.
The problem isn't simply the number of handoffs. It is the friction created at each transition, waiting for information, checking whether something has been completed, re-entering data, or following up with another team.
This tends to show up when:
- Work frequently waits for another team or system before it can move forward.
- Employees spend time checking, forwarding, or reconciling information.
- The same data is handled multiple times during a single workflow.
- Teams rely on email or spreadsheets to coordinate steps that should happen within a defined process.
AI automation can help reduce this friction by handling specific transitions within a workflow, for example, extracting information, determining where it belongs, triggering the next step, or flagging an item that needs human attention.
The opportunity isn't to remove every handoff. It's to reduce the manual coordination required to keep routine work moving.
4. Your Teams Are Struggling to Keep Up With the Volume of Information
P&C insurers work with information from policy systems, claims files, documents, correspondence, and other operational sources. As that volume grows, teams can spend more time finding, reviewing, and organizing information before they can act on it.
The issue isn't necessarily a lack of data. It is the amount of human effort required to turn that information into something usable.
Common indicators include:
- Employees spend significant time searching across different sources for relevant information.
- Important details are buried in large volumes of documents or records.
- Teams rely heavily on manual review before they can move a process forward.
AI automation can help reduce this workload by handling parts of the information-processing process and bringing relevant information into the workflow at the point it is needed. That can help employees spend less time working through information and more time applying their insurance expertise.
When information volume becomes a capacity problem rather than simply a data asset, it may be time to evaluate how AI can help your teams work with it more efficiently.
5. Your Teams Are Spending Too Much Time on Decisions That Follow a Defined Pattern
Not every insurance decision is straightforward, but many operational decisions involve established criteria, available data, and repeatable steps. When experienced employees spend significant time working through these routine decisions manually, their expertise can become tied up in work that follows a relatively consistent pattern.
For example, you may notice:
- Similar cases require employees to repeatedly review the same types of information.
- Teams rely on manual checks to determine the next step in a workflow.
- Different employees spend time working through the same decision process independently.
- Routine decisions are creating delays for cases that actually require deeper judgment.
AI can assist by evaluating available information against defined criteria and helping employees identify the appropriate next step. This doesn't mean handing decision-making entirely to AI. Instead, it can provide a consistent starting point for routine cases while escalating exceptions or higher-risk situations to the appropriate professional.
When a decision process is structured enough to follow a pattern but still consumes substantial employee time, it may be worth evaluating whether AI can assist with the process.
6. Your Existing Technology Can Support AI Integration
An insurer does not need to replace its core technology to start exploring AI automation. What matters is whether the systems involved in a potential workflow can exchange information and support the connections required to introduce a new capability.
You may be ready to explore AI if:
- Key systems have APIs or other reliable methods for exchanging data.
- The information needed for a workflow is available digitally.
- Your technology team can map how information moves between the systems involved.
- New capabilities can be introduced without disrupting critical operations.
AI is only useful when it can access the information it needs and connect with the next step in the workflow. Otherwise, it risks becoming another disconnected layer of technology.
For P&C insurers, the goal should be to integrate AI into a useful workflow rather than add another standalone tool. If your existing environment can support that kind of controlled integration, you may be able to start with a focused AI initiative without undertaking a broader technology overhaul.
Related Read: How to Build Right Core Technology Stack
7. Leadership Has a Clear Business Outcome in Mind
AI should start with a business problem, not with a decision to “implement AI.” For a P&C insurer, that could mean increasing operational capacity, shortening processing times, reducing manual effort, or improving consistency within a specific workflow.
The important question is whether leadership can define what needs to improve and how the result will be measured.
Before selecting a solution, the organization should be able to answer:
- What problem are we trying to solve?
- Where is the current process falling short?
- What would a measurable improvement look like?
- How will we determine whether the investment is worthwhile?
Having clear answers creates a much stronger foundation for an AI initiative. It gives business and technology teams a shared objective and makes it easier to select an appropriate workflow, establish a baseline, and evaluate results after implementation.
If AI has a defined business purpose and a measurable outcome behind it, your organization is in a much stronger position to move from exploring the technology to evaluating a practical implementation.
What to Do Before Implementing AI Automation
Recognizing the signs is only the starting point. Once an insurer identifies a workflow that may benefit from AI, the next step should be a focused assessment rather than trying to automate multiple processes at once.
1. Start With One Workflow
Choose a process with a clear operational challenge, meaningful volume, and defined steps. Starting with one workflow makes it easier to understand the current process and determine whether AI can improve it.
2. Establish a Baseline
Measure how the process performs today. Depending on the workflow, this could include processing time, manual effort, turnaround time, volume, or exception rates. Without a baseline, it is difficult to determine whether automation has created a meaningful improvement.
3. Assess Data and Integration Requirements
Identify what information the workflow depends on, where that information resides, and which systems are involved. This helps determine whether an AI capability can be integrated into the existing process without creating another disconnected layer.
4. Define Success Before Implementation
Set clear measures for what improvement should look like. The objective should be tied to the original business problem, whether that means reducing manual effort, increasing capacity, improving turnaround time, or making a process more consistent.
A focused approach gives insurers a practical way to test AI against a real operational need before committing to broader adoption.
Conclusion
AI adoption doesn't have to begin with a large-scale transformation or an immediate overhaul of existing systems. For P&C insurers, the more practical approach is to start with a clearly defined operational challenge where the process, data, and expected outcome can be understood and measured.
The value of AI is ultimately determined by how well it addresses a real business need. A focused implementation gives insurers an opportunity to evaluate that value in practice, understand what works within their existing environment, and build a stronger foundation for broader adoption.
The goal is not to automate everything. It is to identify where AI can create meaningful operational value, prove it in practice, and scale from there.
For carriers and MGAs ready to explore that opportunity, Practo Insura’s AI Insurance Solutions can help bring AI capabilities into practical insurance workflows.
Insurance Underwriting Automation: Implementation Guide for U.S. P&C Carriers and MGAs
12 Jun, 2026
Most P&C underwriters did not join the industry to chase MVR reports, re-key broker data into a policy administration system, or manually sort submission queues. Yet that is precisely where the majority of their day goes.
The work that actually demands underwriting judgment, risk assessment, pricing decisions, appetite exceptions, portfolio analysis, often sits buried beneath layers of administrative process that have never been redesigned. The result: slower quote turnaround, rising operational costs, and experienced underwriters spending most of their time on tasks a well-configured system could handle automatically.
Insurance underwriting automation is built to fix that. But here is the reality most guides skip: only about 35% of automation initiatives meet their stated goals, according to BCG's analysis of 850 companies. The failure rate is not a technology problem. It is an architecture, data quality, and integration problem, and this guide addresses all three.
What Underwriting Automation Actually Means in 2026
Underwriting automation is not a single product. It is a spectrum of capabilities, and where your organization sits on that spectrum determines where you should start.
At one end: a basic rules engine that auto-approves clean, low-risk submissions based on pre-defined criteria; no ML, no AI, just structured logic. At the other: an agentic underwriting system that ingests submissions in any format, enriches data from external sources in real time, scores risk against your appetite, and routes decisions automatically from submission to bind.
Most mid-market P&C carriers and MGAs sit closer to the left side of that spectrum. Many are still relying on underwriters to manually pull motor vehicle records, re-enter broker PDFs into their PAS, and prioritise their own queues. Automation closes those gaps first, not by replacing underwriters, but by removing the work that should never have required them.
Underwriting automation means removing manual touchpoints from the submission-to-bind workflow so that underwriters spend their time on risk judgment, not data processing.
5 Underwriting Workflows to Automate First Prioritized by ROI
Most carriers ask the same question when they start: where do we begin? The answer is not "everywhere at once." Below are the five workflows ranked by ROI potential and implementation difficulty, based on patterns seen across mid-market automation projects.
1. Submission Triage and Routing
Commercial lines underwriting teams face a structural imbalance: they receive far more submissions than they can evaluate thoroughly, and the volume is growing. Submissions arrive in inconsistent formats: PDFs, emails, ACORD forms, broker portals and someone has to read, classify, and route each one.
Automating triage means the system reads each incoming submission and extracts the key risk attributes, automatically, the moment it arrives.
It then scores the submission against your underwriting appetite criteria and routes it in seconds. No human touchpoint required.
The routing logic is straightforward:
- Clean, in-appetite risks go straight through to bind
- Complex cases go to the referral queue with context already assembled
- Out-of-appetite submissions are declined automatically
In commercial lines, this single workflow typically saves 20–30 minutes per submission. At volume, that is significant underwriter capacity recovered every week — without adding headcount.
STP benchmarks by line of business:
| Line | Achievable STP rate | Notes |
|---|---|---|
| Personal auto | 80–90% | Clean data sources; well-defined rules |
| Homeowners (non-CAT exposed) | 70–85% | Higher in standard territories |
| Simple BOP / small commercial | 60–75% | Depends on data completeness |
| Commercial auto | 40–60% | MVR complexity limits STP ceiling |
| Specialty / E&S lines | 15–35% | Risk complexity requires human judgment |
Benchmarks sourced from ScienceSoft's 2026 underwriting automation research and industry practitioner data.
2. AI Document Processing for Submission Intake
Manual data extraction, reading broker PDFs, pulling figures from loss runs, re-keying ACORD forms into the PAS, is where underwriters lose hours every day. None of that work requires underwriting judgment. It requires reading comprehension and data transfer, which NLP and OCR handle accurately at any volume.
A mid-market personal and commercial auto carrier automating submission intake, before touching any decision logic, has documented quote turnaround reductions from three to five business days down to under four hours. The change is not a new underwriting model. It is removing the manual data re-entry step between broker submission and underwriter review, a result consistent with McKinsey's finding that workflow redesign not the AI tool itself is the single strongest driver of operational improvement.
This workflow is particularly high-value for commercial lines MGAs that receive heterogeneous broker submissions at high volume and must feed structured data into carrier reporting systems.
3. Rules-Based STP for Clean Risks
For personal lines and simple small-commercial submissions that meet your clean-risk criteria, there is no analytical reason for a human to review every file. A well-configured rules engine can handle the full submission-to-bind workflow, data check, eligibility verification, rating, and issuance, without human intervention.
ScienceSoft's research shows that best-in-class automation achieves application processing in under four minutes for standard policies, compared to days or weeks in manual workflows. That speed advantage compounds: faster binding improves broker relationships, reduces quote-to-close abandonment, and lets underwriters concentrate on the complex submissions that genuinely need their judgment.
A personal lines auto carrier starting from under 20% STP pre-automation and reaching 80% STP on standard private passenger submissions after 90 days of rules refinement is a documented outcome consistent with Capgemini's finding that underwriting trailblazers, the top 8% of P&C insurers achieve STP rates in the 70-90% range for standard personal lines. The consistent differentiator is iterating on rules weekly during the first quarter, not configuring once and stepping back.
4. Renewal Pre-Fill and Risk Re-Scoring
Renewal underwriting is frequently more manual than new business despite being lower risk. Underwriters re-pull data, re-check flags, and review accounts that have not materially changed in 12 months. For a mid-size carrier renewing 50,000 policies annually, that represents enormous low-value volume.
Automating renewal workflows means the system pulls updated third-party data before the renewal date, re-scores each account against current appetite criteria, flags accounts with material changes for human review, and pre-fills renewal documents for accounts that pass. This workflow also drives measurable retention improvement: when the system identifies at-risk renewals early, outreach can happen proactively rather than reactively.
A specialty MGA automating renewal pre-fill for a contractors' liability book, pulling updated loss data, re-scoring against appetite, and pre-filling renewal documents, can reduce renewal processing time by 50–65% within the first two quarters, an outcome consistent with BCG's finding that carriers implementing end-to-end AI redesign achieve materially better outcomes than those adding automation to unchanged processes.
5. Referral Queue Management andPrioritization
Even with STP in place for clean risks, complex submissions still require human review. The question is whether underwriters spend time deciding what to work on, or actually working on it.
Automated queue management scores each referred submission by priority, premium size, risk complexity, relationship value, time sensitivity assembles the data package the underwriter needs before they open the file, and routes it based on line of business expertise. The underwriter opens a submission with external data already pulled, appetite criteria already checked, and a risk summary already assembled.
This workflow does not reduce the number of referred submissions. It reduces the administrative overhead of each one, typically by 15–25 minutes per referral.
Why Mid-Market Carriers and MGAs Face Particular Pressure
Three forces are converging in 2026 that make automation a financial necessity rather than a technology aspiration for mid-market operators specifically.
- Combined ratios are deteriorating after the hard market plateau.
The industry-wide combined ratio is forecast to worsen from 97.2% in 2024 to 99% by 2026, according to Deloitte's 2026 Insurance Outlook. Carriers that relied on four years of rate increases to offset operational inefficiency no longer have that buffer. The next margin lever is expense ratio improvement, and manual underwriting processes are one of the largest controllable cost items. - Experienced underwriters are retiring, taking institutional knowledge with them.
McKinsey's Global Insurance Report 2025 found that leading insurers are nearly twice as likely to have prioritized significant technology investment in underwriting operations compared to bottom-quartile performers. The carriers investing now are capturing appetite rules, exception logic, and risk intuition in systems before it walks out the door. - The competitive gap is widening rapidly
McKinsey's Global Insurance Report 2025 also notes that leading insurers achieve loss ratios six percentage points better than competitors, and that operational strategies account for 60% of overall insurer performance. In a softening market where speed to quote determines whether a carrier wins or loses business, the administrative overhead of manual underwriting is a direct competitive disadvantage.
The Automation Technology Stack: Choosing the Right Tool for Each Workflow
One of the most common mistakes carriers make is treating "underwriting automation" as a single technology decision. It is not. Different workflows require different tools, and the wrong match is one of the leading causes of underperforming implementations.
| Technology | Best suited for | Why |
|---|---|---|
| Rules engine | Personal lines, simple BOP, high-volume standard risks | Deterministic, auditable, fast to configure. Ideal for STP where criteria are binary and well-defined. |
| AI document processing (NLP/OCR) | Commercial lines submission intake, loss run analysis | Reads unstructured submissions in any format, extracts data, reduces manual re-keying. |
| ML risk scoring models | Complex commercial, specialty, E&S lines | Identifies non-linear risk signals across hundreds of variables that rules engines miss. |
| Workflow automation / BPM | Referral routing, renewal workflows, queue management | Orchestrates tasks across teams and systems without requiring AI decision-making. |
| Agentic AI | High-complexity submissions requiring multi-step reasoning | Handles entire intake-to-decision workflows autonomously; requires the most governance. |
Most mid-market carriers should not begin with fully autonomous underwriting. A more practical path is to start with a rules engine for high-volume personal lines or simple small commercial risks, then add AI document processing to automate submission intake. ML-based risk scoring should come later, once data quality has been validated. More advanced capabilities, such as agentic AI and full underwriting workbench deployments, are usually better suited for later phases after the core workflow and integration layer are stable.
Why Most Underwriting Automation Projects Underperform
BCG’s 2025 global study of 1,250 companies found that only 35% of transformation initiatives meet their stated goals. In underwriting automation, the failure pattern is usually not the AI model itself. It is poor data quality, weak integration, broken workflows, and missing governance.
Failure point 1: Data quality is treated as an afterthought.
The Capgemini World P&C Insurance Report 2024 found that 70% of insurers cite inconsistent underwriting decisions as a prevailing issue, largely driven by data quality and governance challenges. Inconsistent formats, missing fields, duplicate records, and fragmented legacy data mean automation can produce fast, wrong decisions. Successful carriers clean and validate their data before configuring automation logic.
Failure point 2: Automation is layered onto broken workflows.
McKinsey’s 2025 State of AI report found that high-performing organizations are nearly three times more likely to redesign workflows around AI rather than simply add AI to existing processes. If a manual, approval-heavy workflow is automated without redesign, the result is only a faster version of the same inefficient process.
Failure point 3: PAS integration is underestimated.
BCG’s 2026 Executive Perspectives on P&C Insurance found that 35% of insurance applications still run on legacy technology stacks that are not cloud-ready. When the automation layer cannot communicate with the PAS, rater, or policy issuance module, the workflow breaks at the final step and manual work returns. Leading carriers test PAS integration early, not after decision logic is already configured.
Failure point 4: Governance is added too late.
KPMG’s 2025 analysis of technology implementation failures cites poor data governance and unclear requirements as common failure drivers. In underwriting automation, that means undocumented rules, no bias-testing process, and no defined escalation path for edge cases. Carriers that document rules, assign ownership, and define human-review criteria before go-live reduce compliance and rollback risk.
How Automation Connects to Your PAS and Rater Engine: The Integration Layer Most Carriers Miss
Underwriting automation that cannot talk to your policy administration system delivers half the value at full cost. The integration requirement is specific:
- Your rater must receive dynamic inputs from the automation layer.
If the rules engine approves a risk but your rating engine requires manual data re-entry to price it, you have automated the decision but not the workflow. The data captured at submission should flow forward to the rater without human intervention. - Your PAS must act on automated decisions.
When the rules engine approves a clean-risk submission, the PAS should issue the policy automatically via API. This requires deliberate integration work, it does not happen by default. - A single data capture at submission must feed every downstream system.
Bordereaux reporting, carrier data feeds, compliance documentation, and billing all need accurate data from the same submission record. Every additional re-entry point introduces error and compliance risk.
Carriers operating on cloud-native, API-first PAS platforms have a structural advantage here. The right core tech stack is a prerequisite to automation at scale, not something to address after implementation. Legacy PAS platforms often require significant middleware development to achieve the same data flow, which is worth planning for in the project budget before vendor selection.
For MGAs, the integration requirement extends to carrier partner systems. Your automation must produce the data formats, bordereaux structures, and reporting outputs your carriers contractually require. An automation layer that operates as a silo from your MGA management system creates reconciliation work that erodes the efficiency you built.
Related Read: How to Build Right Core Technology Stack for P&C Insurer
Build vs Buy: How to Choose the Right Approach for Your Organization
Every carrier and MGA evaluating underwriting automation eventually hits the same fork in the road: do we build this internally, buy a platform, or configure a pre-built solution? There is no universal answer, but there is a framework for making the right call based on your size, technical maturity, and competitive priorities.
The four options, and who each suits
Option 1: Build internally
You develop the rules engine, data integrations, and workflow logic using internal engineering resources or contract developers.
Best for: Large carriers ($1B+ GWP) with dedicated engineering teams, a proprietary risk model that is genuinely differentiated, and a multi-year runway for development and maintenance.
Reality for mid-market: Most mid-market carriers do not have the engineering capacity to build, maintain, and iterate on an underwriting automation system while also running daily operations. McKinsey's research shows companies that redesign workflows end-to-end achieve 3× better AI outcomes than those that treat it as a technology project, and that redesign work competes directly with build capacity.
Option 2: Buy a standalone automation platform
You purchase a dedicated underwriting workbench or automation tool and integrate it with your existing PAS and rater.
Best for: Carriers with a functioning PAS that has open APIs and a reasonably clean data layer. Works well when the existing core system is sound and only the underwriting workflow layer needs upgrading.
Watch for: Integration cost is frequently underestimated. BCG's 2026 P&C Executive Perspectives found that 35% of insurance applications still run on legacy stacks that are not cloud-ready, buying a modern automation tool and connecting it to a legacy PAS often requires more middleware development than the tool itself costs.
Option 3: Buy + configure (SaaS with configurable rules)
You deploy a pre-built underwriting automation platform where the rules engine, workflow logic, and data integrations are configurable by your underwriting and product teams, without requiring developer involvement for routine changes.
Best for: Mid-market carriers and MGAs that need to be live in months, not years, and want underwriting and product staff to own the rules without IT dependency. A no-code and low-code configuration is particularly valuable for MGAs managing high volumes of products across multiple lines who need to respond to market opportunities quickly.
This is the most common starting point for $100M–$500M GWP carriers and growing MGAs.
Option 4: Modern PAS with native automation capabilities
Rather than adding a separate automation tool on top of your existing core system, you move to a PAS that includes built-in rules engine, rater integration, workflow orchestration, and bordereaux generation with automation as a native capability rather than a bolt-on.
Best for: Carriers and MGAs that are also evaluating a PAS upgrade or replacement. If your current PAS is a barrier to integration, solving the PAS problem and the automation problem simultaneously is significantly more cost-effective than solving them sequentially.
The decision framework
Ask these four questions before choosing a path:
| Question | Build Internally | Buy Standalone | Buy + Configure | PAS-Native Automation |
|---|---|---|---|---|
| Do you have a dedicated engineering team? | Required | Helpful | Not required | Not required |
| Is your current PAS API-ready? | Helpful | Required | Helpful | Not required |
| Do you need to launch within 12 months? | Rarely realistic | Possible | Likely | Likely |
| Is your underwriting logic highly proprietary? | Best fit | Moderate fit | Moderate fit | Lower fit |
| Do business users need to update rules without IT? | Difficult | Depends on vendor | Yes | Yes |
| Is your current PAS already a constraint? | Does not solve it | Does not solve it | Partially solves it | Best fit |
| Best suited for | Large carriers with strong engineering teams | Carriers with modern API-ready cores | Mid-market carriers and MGAs | Carriers or MGAs replacing legacy PAS |
What Does Underwriting Automation Cost? A Budget Framework for 2026
Cost is the question most guides avoid answering. The honest answer is that investment ranges vary significantly based on organization type, build-vs-buy decision, and scope of the first phase.
The table below provides indicative budget guidance based on observed SaaS and configure-and-deploy market pricing. These are directional estimates, not quoted prices, actual costs depend on vendor, scope, data complexity, and legacy integration requirements. Use them for initial scoping conversations, not final budgeting.
| Organisation type | Typical Phase 1 investment (U.S.) | What it typically covers |
|---|---|---|
| Small MGA (under $50M GWP) | $50,000–$150,000 | SaaS rules engine, submission intake automation, and limited integration work for a single line of business |
| Mid-market MGA ($50M–$200M GWP) | $150,000–$500,000 | Configurable underwriting automation, STP workflows, renewal automation, and PAS/rater integration |
| Regional carrier ($200M–$500M GWP) | $500,000–$1.5M | Underwriting workbench, PAS integration, data validation layer, and rollout across multiple lines |
| Mid-size carrier ($500M–$1B+ GWP) | $1M–$5M+ | Enterprise implementation including legacy system integration, workflow redesign, governance controls, compliance requirements, and multi-line deployment |
Where budget typically goes in a Phase 1 project (indicative estimates based on practitioner experience, actual allocation varies by project):
- Licensing / platform fees: 30-45% in SaaS deployments; the smallest component in custom builds
- Integration and data work: 35–50% in connecting to existing PAS, MVR providers, and carrier reporting systems is consistently the most underestimated line item
- Rules configuration and testing: 10–20% in documenting, building, and validating appetite rules before go-live
- Compliance and governance setup: 5–10% in audit trail design, bias testing protocol, NAIC documentation
The hidden cost most budgets miss: data quality remediation. If your existing PAS data has inconsistencies, duplicate records, non-standardised fields, legacy migration artefacts, cleaning it before automation go-live typically adds meaningful unplanned cost.
ROI timeline: A 12–18 month payback period for underwriting automation is a commonly cited industry benchmark, driven primarily by underwriter capacity reallocation and improved broker hit rates from faster quote turnaround. Independently verified ROI timelines for underwriting automation specifically are not widely published, so treat this as a directional range rather than a guarantee.
How to Get Started: A 4-Step Incremental Approach
The most common mistake mid-market carriers make is treating underwriting automation as an all-or-nothing transformation. The second most common mistake is waiting for perfect data before starting. Neither works.
Step 1: Audit one high-volume, low-complexity line
Select a single line of business, personal auto, homeowners, or simple BOP, where submission volume is high, risk criteria are well-defined, and your appetite rules are already documented in some form. This becomes your automation pilot. Do not start with commercial casualty or specialty lines.
Step 2: Clean data and automate triage and intake for that line only
Before touching any decision logic, address data quality for your pilot line and implement automated submission intake and third-party data pulls. This step alone recovers significant underwriter time and validates your data foundation before automated decisions are made on top of it.
Step 3: Implement STP connected to your rater and iterate weekly
Configure rules-based auto-approval for clean-risk submissions in your pilot line. Critically, confirm the integration to your PAS and rater before go-live so that approved submissions issue automatically. Monitor results weekly for the first 90 days. Adjust rules as you observe the submission population. STP rates improve meaningfully with iteration in the first quarter.
Step 4: Expand to renewal workflows and additional lines
Once one line is operating with reliable STP, clean data flows, and a functioning audit trail, expansion to renewal pre-fill and additional lines follows the same pattern. Each line benefits from the infrastructure and governance framework built in Steps 1–3.
This approach takes 6–12 months to reach meaningful scale for a mid-market carrier or MGA. It is slower than a full-platform replacement and significantly lower risk, and the carriers that follow it have materially better outcomes than those who attempt to automate everything at once.
Is Your PAS Ready for Automation?
The sections above converge on the same practical question: does your current policy administration system satisfy the four integration requirements that underwriting automation depends on?
Specifically: does it expose real-time APIs, accept dynamic rater inputs, generate bordereaux natively, and include a workflow orchestration layer, without requiring a middleware project to connect each piece?
If the answer is no, the most cost-effective path is often to solve the PAS problem and the automation problem together rather than sequentially. Retrofitting automation onto a PAS that was not designed for it is one of the most common sources of project overrun in mid-market underwriting technology programmes.
Practo Insura's policy administration system is built with these four requirements as native capabilities: an API-first architecture, a built-in Rapid Rater engine, real-time MVR and third-party data integration, and workflow orchestration for referral routing and compliance escalation, designed specifically for mid-size U.S. P&C carriers and MGAs.
If you are evaluating whether your current PAS can support your automation roadmap, request a demo to see how the platform connects to your existing systems and what a phased automation implementation would look like for your lines of business.
Why Claims Data Matters in Product Design for U.S. P&C Insurer
03 Jun, 2026
Claims data has traditionally been treated as a record of past losses, used mainly for reserving, reporting, and post-event analysis. But in today's U.S. P&C market, where repair severity, litigation exposure, climate volatility, and emerging risks are changing faster than traditional product cycles, claims data is becoming a strategic input for product design, pricing, and underwriting decisions.
The real challenge is no longer whether insurers have claims data, every carrier does. The challenge is how quickly they can convert claims signals into business action. As the gap between changing risk conditions and organizational response widens, claims intelligence is becoming a critical capability for improving underwriting performance, product relevance, and long-term profitability.
What is Detection Gap in Modern Insurance Product Design
Most carriers do not struggle because they lack claims data. They struggle because there is often a significant gap between when a claims trend emerges and when the organization takes action.
Consider a common auto insurance example. Claims teams may start seeing higher repair severity for specific vehicle segments due to increasing ADAS calibration requirements, longer repair cycles, or more expensive replacement parts. The signal exists. The data exists. The problem is that product, underwriting, and pricing teams may not see that trend until months later through formal reviews or profitability reporting.
That delay creates what can be called the Detection Gap, the period between when claims data first signals a meaningful change in risk and when the organization responds with a pricing, underwriting, or product adjustment.
Why the Detection Gap Matters
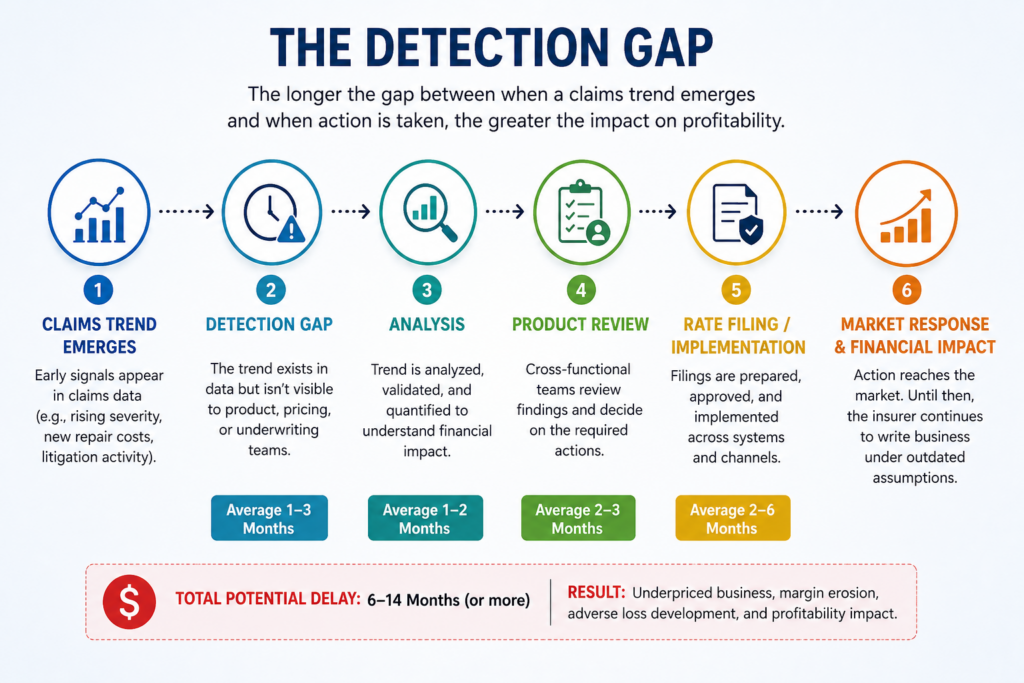
The financial impact of a claims trend is rarely immediate. Instead, it accumulates quietly across hundreds or thousands of policies before it becomes visible in portfolio-level metrics.
- A severity trend may emerge today.
- A product team may detect it three months later.
- Analysis and validation may take another two months.
- A rate filing may require several more months before implementation.
By the time corrective action reaches the market, an insurer may have spent nearly a year writing business under assumptions that no longer reflect actual risk conditions.
The challenge is not limited to auto insurance. Similar detection gaps appear across P&C lines through:
- emerging weather-related loss patterns
- litigation-driven bodily injury severity
- coverage disputes and claims escalation trends
- organized fraud activity
- geographic concentration risk
In many cases, claims activity identifies these issues long before they appear in underwriting profitability reports.
From Claims Data to Business Action
Closing the detection gap requires insurers to think differently about claims information.
Claims data alone has limited value. What matters is how quickly that data becomes actionable intelligence.
The progression looks like this:
Claims Data → Pattern Detection → Business Decision → Product Action
The faster an organization moves through this cycle, the faster it can:
- adjust pricing assumptions
- refine underwriting appetite
- redesign coverage structures
- manage emerging risks
- protect portfolio profitability
This is why leading insurers increasingly treat claims intelligence as a strategic product management capability rather than a claims reporting function.
Why Claims Data Has Become a Strategic Product Asset
Claims data was once treated mainly as an operational record: what happened, what was paid, and how claims were handled. But for modern P&C insurers, that view is too limited.
Every product decision eventually shows up in claims. Pricing decisions affect profitability. Underwriting rules affect loss frequency. Coverage wording affects disputes. Deductibles affect claim behavior. Geographic expansion affects concentration risk.
That is why claims data has become a strategic product asset. It helps insurers validate whether product assumptions still match real-world risk conditions before problems appear in high-level profitability reports.
For carriers, MGAs, and reinsurers, the value is not simply having more claims data. The value is converting claims signals into faster pricing, underwriting, coverage, and portfolio decisions.
1. Validating Pricing and Underwriting Decisions
Pricing and underwriting decisions are built on assumptions. Claims data is where those assumptions are tested against actual loss behavior.
A rate plan may assume that a certain vehicle class, territory, driver profile, or coverage type carries a predictable level of risk. But once claims begin developing, insurers can see whether that assumption still holds. This is especially important in auto insurance, where repair severity, bodily injury trends, litigation involvement, and vehicle technology can change the economics of a segment quickly.
The impact is already visible in repair data. According to industry research, the average total cost of repair has increased 96.4% since 2009, rising from approximately $2,405 to more than $4,720 in 2024. Nearly half of that increase occurred within the last five years alone. ADAS-related costs are a major contributor. Calibration fees increased from $168 in 2017 to $488 in 2024, while diagnostic-related costs per 100 claims grew from roughly $580 to more than $21,300.
At the same time, auto insurance claims have increased 14% since 2020, while claims severity has risen 36%. For product and underwriting teams, these trends demonstrate how quickly actual loss costs can diverge from historical pricing assumptions.
What Claims Data Helps Validate
Claims data can show whether:
- certain vehicle types are producing higher severity than expected
- specific territories are generating more frequent or more expensive claims
- bodily injury trends are worsening in particular states
- deductible structures still make sense for current repair costs
- underwriting rules are attracting the right risk profile
- rating variables are still aligned with actual loss outcomes
For example, if newer vehicles with advanced safety systems are consistently producing higher repair costs than expected, the issue is not just claims severity. It may indicate that the current pricing model, deductible design, or underwriting assumptions need to be refined.
What Insurers Can Do With This Insight
Product and underwriting teams can use claims intelligence to make targeted changes, such as:
- revising rating factors
- adjusting deductible options
- tightening eligibility rules
- updating underwriting guidelines
- modifying territory assumptions
- flagging specific segments for pricing review
- redesigning coverage structures where loss behavior has changed
This prevents claims insight from staying trapped inside claims operations. It turns the data into a practical input for product and underwriting decisions.
The Result
When insurers use claims data to validate pricing and underwriting assumptions, they gain a clearer view of where the product is still working and where it is drifting away from real risk.
The result is sharper segmentation, better risk selection, stronger rate adequacy, and more disciplined portfolio management.
Related Read: How Insurers Use Predictive Analytics to Improve Underwriting and Risk
2. IdentifyingCoverage Gaps and Emerging Risks
Claims activity often reveals a different kind of product problem: not whether the price is right, but whether the coverage itself still works in the real world.
A product may be priced correctly and still create friction if policy wording is unclear, endorsements are outdated, limits no longer reflect current costs, or new exposures were not considered when the product was designed. These issues usually surface during claims, when customers test the product under actual loss conditions.
What Claims Data Reveals
Claims data can show:
- which coverages generate the most disputes
- where policy language creates confusion
- which endorsements are producing unexpected loss behavior
- whether limits or deductibles still match current repair and replacement costs
- where new risks, such as EV repairs, severe weather, or litigation trends, are creating product pressure
For example, an auto insurer may find that rental reimbursement limits are no longer adequate because repair cycle times have increased. A property insurer may see repeated disputes around water damage or storm-related exclusions. An MGA may discover that a niche endorsement is being used differently than originally expected.
What Insurers Can Do With This Insight
Product teams should treat these patterns as design feedback, not just claims friction.
That means insurers can:
- review dispute trends by coverage type
- analyze escalation patterns tied to specific policy wording
- reassess limits, deductibles, and exclusions against current claim realities
- update endorsements where loss behavior has changed
- involve claims and compliance teams before product changes are finalized
The Result
Using claims data this way helps insurers close coverage gaps before they become larger profitability, litigation, or customer experience problems.
It also makes product design more grounded in real claim behavior, not just market assumptions, competitor forms, or historical coverage structures.
3. Reducing Fraud and Claims Leakage
Fraud is not always obvious at the individual claim level. One inflated repair supplement, one represented injury claim, or one unusual billing pattern may look isolated. The real signal appears when similar patterns repeat across vendors, geographies, coverages, or claim types.
That is where claims intelligence becomes valuable. It helps insurers move beyond claim-by-claim review and identify leakage patterns that point to broader product or process vulnerabilities.
A 2024 study by CLARA Analytics found that AI-driven cohort modeling identified potential fraud indicators within two weeks of claim submission. Approximately 9% of open claims were flagged as strong SIU referral candidates, with the model identifying suspicious activity at a rate comparable to experienced adjusters but significantly earlier in the claim lifecycle.
Where Leakage Often Shows Up
Common signals include:
- repeated supplement requests from specific repair vendors
- abnormal medical billing patterns
- recurring use of the same coverage provisions
- staged accident indicators
- unusual claim timing or clustering
- claim types with higher-than-expected escalation rates
For example, if a specific endorsement is repeatedly involved in questionable claims, the issue may not be limited to fraud investigation. The endorsement itself may need clearer eligibility rules, stronger documentation requirements, or tighter claim controls.
How Insurers Can Respond
Insurers can reduce leakage by:
- standardizing vendor and provider tracking
- connecting SIU findings with product and underwriting teams
- reviewing claim pathways that are repeatedly exploited
- tightening documentation requirements where abuse patterns appear
- monitoring fraud indicators by coverage, vendor, geography, and claim type
Result
This helps insurers reduce avoidable claim costs while improving product discipline.
More importantly, it turns fraud detection into a product feedback mechanism. If claims data shows where the product is being exploited, insurers can redesign the exposure instead of only investigating it after the loss occurs.
Related Read: 5 Questions Every Carrier Must Ask Before Launching a New Line of Business
4. Improving Product Profitability and Portfolio Performance
Growth can hide weakness in a P&C portfolio. A product may continue adding premium while certain geographies, coverages, or customer segments quietly produce more volatility than expected.
Claims intelligence helps insurers separate healthy growth from fragile growth.
According to AM Best, the P&C industry's combined ratio improved from 101.6 in 2023 to 96.6 in 2024, driven in part by stronger pricing discipline, improved underwriting performance, and broader use of analytics.
Where Portfolio Pressure Often Appears
Claims data can reveal:
- geographies with concentrated or worsening loss activity
- coverages creating unexpected volatility
- segments requiring stronger reserve attention
- claim types affecting reinsurance confidence
- products where growth is outpacing risk control
- business classes producing unstable loss development
For example, a carrier may expand successfully in written premium, but claims activity may show that one region is becoming more exposed to weather losses or litigation-heavy claim behavior. That does not always mean the product should exit the market. It may mean the insurer needs tighter appetite rules, different deductibles, revised limits, or a different reinsurance view.
How Insurers Can Respond
Product, underwriting, and portfolio teams can use claims intelligence to:
- identify where growth should be accelerated, slowed, or restricted
- evaluate product performance below the portfolio-average level
- reassess limits, deductibles, and appetite by region or segment
- use claim volatility trends in reinsurance planning
- decide whether certain products need redesign before expansion continues
Result
Claims-informed portfolio management helps insurers grow with more discipline.
It gives leadership a clearer view of which parts of the portfolio are sustainable, which require correction, and which may create future volatility if left unmanaged.
5. Accelerating Product Innovation and Customer Experience Improvements
Product innovation does not always start with a new idea. Sometimes it starts with repeated claims patterns that show where customers need better protection, clearer service, or a product built for newer risk behavior.
Claims data gives insurers a practical view of how products perform after purchase, when the policyholder actually needs the coverage.
In 2024, more than 21 million U.S. policyholders shared telematics data with their insurer, a 28% compound annual growth rate since 2018. Carriers that connected telematics data to actual claims outcomes rather than just pricing models reported up to eight points of combined operating ratio improvement purely from the use of telematics data in claims.
Where Innovation Signals Appear
Claims activity can reveal:
- new protection needs that current products do not address
- claim journeys that create avoidable friction
- service gaps around repair, replacement, or settlement
- opportunities for specialized endorsements
- areas where digital claims support could improve the experience
- risk behaviors that may support usage-based or behavior-based products
For example, recurring EV repair complexity may support a more specialized auto product. Repeated delays in repair coordination may point to the need for stronger repair network partnerships or better digital claims updates.
How Insurers Can Respond
Product and innovation teams can use claims intelligence to:
- validate new product ideas with actual loss experience
- design endorsements around real customer needs
- improve claims communication and service workflows
- modernize products around EVs, telematics, embedded insurance, or usage-based models
- connect claims insights with customer retention and renewal strategy
Result
Claims-informed innovation helps insurers move beyond competitor-driven product development.
It gives them a clearer way to modernize products based on real policyholder behavior, actual loss outcomes, and service friction that directly affects customer trust.
Related Read: 5 Types Usage-Based Auto Insurance
Which Claims Signals Actually Require Product Action?
This section is important because one of the biggest challenges for carriers is not a lack of claims data. It is knowing which signals deserve action and which are simply noise.
Not every increase in claim activity requires a pricing change, product redesign, or underwriting adjustment. The most effective insurers focus on signals that indicate a structural change in risk, profitability, or customer behavior.
High-Priority Signals
These are signals that should typically trigger product, pricing, or underwriting review.
- Significant Severity Increases: When claim severity rises consistently within a specific segment, geography, or coverage type, it may indicate that pricing, deductibles, or underwriting assumptions are no longer aligned with actual loss costs.
- Recurring Coverage Disputes: A growing volume of disputes tied to the same policy provision often signals a product design issue rather than an isolated claims problem.
- Emerging Geographic Concentration: Rising claims activity in a specific region may indicate changing weather patterns, theft trends, litigation exposure, or other evolving risks that require product attention.
- Shifts in Litigation Activity: Changes in attorney involvement, bodily injury severity, or settlement patterns can quickly alter the economics of a product.
Medium-Priority Signals
These signals deserve monitoring but may not immediately require action.
- Temporary Frequency Fluctuations: Short-term spikes caused by seasonality, weather events, or unusual market conditions should be validated before product changes are made.
- Localized Vendor Performance Issues: Problems tied to a specific repair network, contractor, or service provider may require operational intervention before product intervention.
- One-Time Regulatory or Market Events: Certain events may temporarily influence claims outcomes without creating long-term product implications.
Low-Priority Signals
Some claims trends create visibility but rarely justify immediate product action on their own.
Examples include:
- isolated large losses
- individual fraud cases
- short-term claim anomalies
- single-event severity spikes
These events should be monitored but not automatically drive product decisions.
The Goal Is Prioritization
The objective is not to react to every claims trend. It is to identify the signals most likely to affect pricing adequacy, underwriting performance, coverage effectiveness, or portfolio sustainability.
Insurers that establish clear decision triggers can respond more consistently and avoid both overreacting to noise and underreacting to meaningful change.
Conclusion
Claims data is no longer just a record of past losses. It is becoming a product strategy asset for insurers that want to understand how risk is changing in real time.
The real advantage is not having claims data, every carrier has it. The advantage comes from detecting meaningful signals faster and turning them into product, pricing, and underwriting decisions before issues affect profitability or portfolio performance.
As an insurance strategic consultant, Practo Insura helps carriers, MGAs, and reinsurers connect claims intelligence with product strategy, underwriting discipline, and modernization initiatives, helping them build more adaptive products for changing risk conditions.
What Is Subscription Auto Insurance and How to Build It for P&C Insurer in USA
15 Apr, 2026
Auto insurance was designed for a market built on long-term vehicle ownership, predictable driving habits, and fixed policy terms.
But mobility is changing. Consumers now expect simpler billing, faster servicing, and models that align with how they access and use vehicles. As subscription-based experiences expand across industries, insurance is also beginning to shift from a rigid annual product to a more adaptable, service-led model.
That is where subscription auto insurance is gaining relevance. It gives insurers a way to align coverage with modern mobility expectations while offering customers a more flexible and convenient experience.
Understanding Subscription Auto Insurance
Subscription auto insurance is more than a shorter policy term. It is a different way of offering coverage.
Instead of putting customers into a fixed 6- or 12-month contract, this model usually works on a monthly recurring basis. Customers pay a flat monthly amount, coverage renews automatically, and changes like cancellation, upgrades, or vehicle swaps are meant to be much easier to handle.
What makes this model different is the way it is structured. Traditional auto insurance is built around a one-time policy purchase that is reviewed later at renewal. Subscription insurance is structured as a continuously active coverage model rather than a fixed-term contract.
It can be offered in two main ways:
- as a standalone monthly insurance product
- as part of a larger mobility package
That larger package may include:
- vehicle access
- maintenance
- roadside assistance
- insurance coverage under one monthly payment
This changes the role of insurance. Instead of being a separate product customers buy on its own, it becomes part of a broader mobility experience.
This also sets it apart from PAYG and PHYD models. PAYG is based on how much a person drives. PHYD is based on how a person drives. Subscription auto insurance is different because it is built around flexibility, simplicity, and convenience, not mileage tracking or behavioral scoring.
So, subscription auto insurance is not just a pricing change. It is a product and distribution model that makes coverage easier to package, manage, and deliver in a more service-driven way.
How Subscription Auto Insurance Works
Subscription auto insurance is designed to make coverage easier to start, manage, and continue.
In most cases, the journey begins digitally. Customers sign up online, choose a vehicle or coverage plan, and pay a flat monthly fee. Once activated, coverage renews automatically each month unless the customer decides to change or cancel it.
A typical customer journey looks like this:
- sign up through an app or website
- choose a vehicle, coverage tier, or bundled plan
- pay a monthly subscription fee
- start coverage immediately or on the selected date
- renew automatically each month
- upgrade, switch, or cancel with minimal friction
This makes the experience feel simpler than a traditional auto policy. Instead of managing a long-term insurance contract, the customer interacts with coverage as an ongoing monthly service.
How to Design a Subscription Pricing Model That Works
Pricing subscription auto insurance is not just about setting a monthly fee. The real challenge is designing a model that feels simple and predictable for customers, while still being financially sustainable for the insurer.
Unlike traditional policies, you are not pricing a fixed-term contract. You are pricing an ongoing relationship where customers can change plans, vehicles, and coverage more frequently. That makes pricing more sensitive to churn, duration, and usage patterns over time.
Core Pricing Models Used in Subscription Insurance
| Pricing Approach | How it Works | Best for | Main Advantage | Main Risk |
|---|---|---|---|---|
| Flat monthly pricing | One recurring fee for a standard coverage package | Simple direct-to-consumer offerings | Easy to understand and market | Can underprice risk if segmentation is weak |
| Tiered subscription plans | Multiple monthly plans based on coverage/service level | Insurers wanting flexibility without too much complexity | Supports upsell and clearer customer choice | Requires careful product design across tiers |
| Bundled pricing | Insurance included with vehicle/services in one fee | OEM, car subscription, mobility partnerships | Strong convenience and embedded distribution | Margin visibility and partner cost allocation can get difficult |
What Insurers Must Build Beneath the Monthly Price
Even if the monthly price looks simple to the customer, the pricing logic underneath needs to be carefully structured.
- Base monthly premium logic: Define the recurring price based on coverage level, vehicle category, and target segment. It should be built for a subscription model, not created by simply splitting an annual premium into 12 parts.
- Risk segmentation: Adjust pricing internally using factors like driver profile, geography, and vehicle type. This keeps pricing disciplined without making the customer experience feel complex.
- Bundle cost allocation: Separate the insurance portion from vehicle access or other bundled services. This is important for understanding true margins and avoiding hidden profitability issues.
- Mid-cycle pricing rules Set clear logic for vehicle swaps, plan upgrades, downgrades, or coverage changes during the subscription period. These changes should be handled smoothly without unnecessary friction.
- Proration logic: Calculate fair charges when customers make changes mid-month. This helps maintain billing accuracy while reducing revenue leakage.
Designing Pricing for Flexibility (Where Most Models Fail)
Subscription models break down when pricing cannot adapt to real-world behavior.
Your pricing design must support:
- frequent customer changes without manual intervention
- real-time or near real-time plan adjustments
- consistent billing despite mid-cycle modifications
- smooth transitions between plans or vehicles
If these are not built into pricing logic, operational friction quickly erodes the customer experience.
How to Evaluate Pricing Performance
Subscription auto insurance cannot be evaluated using traditional annual metrics alone. Performance needs to be tracked continuously, with a focus on customer behavior over time.
- Customer Lifetime Value (LTV): Measures the total value a customer generates over their full subscription period. This should factor in premium collected, claims cost, servicing cost, and retention duration. A strong model ensures LTV consistently exceeds acquisition and servicing costs.
- Monthly Churn Rate: Tracks the percentage of customers who cancel each month. Even small increases in churn can significantly reduce profitability, especially if acquisition costs are high.
- Average Subscription Duration: Indicates how long customers typically stay active. Longer durations improve profitability by spreading acquisition and onboarding costs over time. It also signals whether the product is delivering sustained value.
- Loss Ratio by Customer Cohort: Instead of looking only at overall loss ratios, insurers should track performance by customer groups (e.g., new vs retained customers, plan tiers, acquisition channels). This helps identify where risk or pricing issues are concentrated.
- Revenue Stability (Monthly Premium Consistency): Measures how predictable monthly income is across the portfolio. High volatility may indicate pricing gaps, churn issues, or overexposure to short-term customers.
- Plan Mix and Upgrade/Downgrade Trends: Tracks how customers move between pricing tiers. This helps insurers understand whether higher-value plans are being adopted and where revenue leakage may occur.
Operational Model Requirements for Subscription Insurance
Subscription auto insurance may feel simple to the customer, but it creates a more demanding operating model for the insurer.
Traditional auto insurance follows a fixed sequence: quote, bind, issue, then renew at the end of the policy term. Subscription models work differently. They run on a continuous lifecycle, where coverage is renewed monthly and customers may change plans, vehicles, or service levels far more often.
That means insurers cannot rely on operations designed for static policy administration. They need processes built for ongoing change.
Core Operational Capabilities
To run this model effectively, insurers need a few capabilities in place.
- Recurring billing and invoicing: The system must support monthly collections, payment retries, and proration when customers make changes mid-cycle.
- Rolling policy lifecycle management: Coverage needs to be managed as an active, ongoing service rather than a policy that only changes at renewal.
- Fast activation and deactivation: Customers expect coverage to start, stop, or switch quickly, without manual delays or back-office bottlenecks.
- Mid-cycle change handling: Operations must support vehicle swaps, plan upgrades, downgrades, and coverage edits at any point in the subscription period.
- Customer self-service support: Policyholders should be able to manage payments, plan changes, and account updates through digital channels without depending on manual support for every request.
Key Operational Risk Areas
The flexibility that makes subscription insurance attractive also creates operational pressure.
- Billing failures can disrupt active coverage: A missed or failed payment is not just a finance issue. If not handled properly, it can create coverage gaps, customer disputes, and compliance concerns.
- High churn increases processing volume: Frequent onboarding, offboarding, and account changes raise operational workload and can quickly strain teams that are still built around annual policy cycles.
- Bundled services increase coordination risk: When insurance is packaged with vehicle access, maintenance, or roadside services, multiple systems and partners must remain synchronized. If they do not, customer experience and margin control both suffer.
Technology Requirements for Subscription Auto Insurance
Subscription auto insurance cannot run effectively on traditional policy systems alone. The model depends on continuous updates, recurring billing, and real-time flexibility, which most legacy systems are not designed to handle.
To support this, insurers need a technology stack that enables ongoing policy orchestration, not just one-time policy issuance.
Core Technology Capabilities
To build and scale a subscription model, insurers should focus on these key components:
- Policy systems that support incremental updates:Policy administration system should allow vehicle swaps, plan changes, and coverage edits without requiring full re-issuance or manual intervention. Systems built only for fixed-term policies will struggle with this level of change.
- Billing systems designed for continuous adjustments: Monthly billing alone is not enough. The system must handle proration, failed payments, retries, and mid-cycle changes accurately and consistently at scale.
- Pricing engines that respond to event-based triggers: Rating logic should be able to update pricing when customers make changes, not just at quote or renewal. This includes plan upgrades, vehicle changes, and coverage modifications.
- Integration layers that support real-time coordination: If the product connects with OEM platforms, mobility providers, or third-party services, integrations need to be API-first and responsive. Delays between systems can create billing mismatches and poor customer experience.
- Customer platforms that enable self-service: Customers should be able to manage subscriptions, payments, and changes without manual support. This requires tightly connected front-end and core systems.
- Data systems that track behavior over time: Subscription models require visibility into churn, plan movement, and cohort performance. Data systems need to support continuous tracking, not just periodic reporting.
Integration Requirements
Subscription auto insurance rarely operates as a standalone system. In many cases, it sits inside a broader mobility ecosystem, which means insurers need strong integration across both internal and external platforms.
At a minimum, the technology stack should connect with:
- vehicle subscription platforms
- OEM and dealer systems
- mobility or ride-sharing applications
- payment gateways and billing providers
These integrations are essential for keeping pricing, billing, policy changes, and customer experience aligned across the full journey. If systems do not stay synchronized, even a well-designed product can create friction for both the insurer and the customer.
Related Read: How to Build Right Core Technology Stack for P&C Insurer in the USA
How Underwriting Changes in Subscription Auto Insurance
Underwriting in subscription auto insurance needs to work in a more dynamic environment, where coverage may change more often and customer relationships may be shorter or less stable over time. Instead of relying mainly on fixed-term assumptions, insurers need underwriting rules that can support ongoing adjustments while still protecting portfolio quality.
In practice, the biggest changes show up in a few areas:
- Eligibility needs to be tighter upfront: Clear rules are needed for which driver profiles, vehicle types, and coverage combinations are suitable. This prevents high-variability risks from entering a model designed for speed and flexibility.
- Re-rating becomes more event-driven: Pricing and underwriting should be reassessed when key changes occur, such as vehicle swaps, plan upgrades, or coverage edits. Trigger-based logic helps manage these changes without slowing down the experience.
- Shorter exposure periods need closer monitoring: Profitability can shift faster when customers stay for shorter durations. For example, a customer subscribing for one month and filing a claim early in the cycle can significantly impact margins.
- Entry and exit behavior matters more: Customers may activate coverage during high-usage periods and cancel afterward. Monitoring these patterns is critical to avoid adverse selection.
- Portfolio monitoring becomes more important: Underwriting needs to track performance by cohort, plan type, segment, vehicle category, and subscription duration to identify weak patterns early and adjust rules accordingly.
The key change is that underwriting becomes less about one-time risk assessment and more about managing risk across a product that is designed to stay flexible.
How Claims Management Needs to Change in Subscription Auto Insurance
Claims management in a subscription model needs to be built for speed, continuity, and coordination, not just settlement. Because customers can enter, exit, or modify coverage more frequently, the claims function has to operate in a way that support a model with frequent policy updates and shorter customer lifecycles.
In practical terms, insurers should focus on the following changes:
- Faster FNOL and intake workflows: Claims reporting should be instant and digital-first, with minimal steps. This reduces friction at the most critical moment and aligns with the overall subscription experience.
- Early-stage claim tracking and controls: Claims occurring soon after activation should be monitored closely, as they have a higher impact on profitability. This requires better visibility into claim timing relative to subscription start.
- Integrated service workflows: Claims systems need to connect directly with repair networks, roadside assistance, and service partners. This ensures faster resolution and avoids delays caused by disconnected processes.
- Real-time status and communication: Customers should be able to track claim progress, upload documents, and receive updates digitally. Lack of visibility can quickly impact satisfaction and retention.
- Cohort-based claims analysis: Instead of only tracking overall claims performance, insurers should analyze claims by plan type, vehicle category, acquisition channel, and subscription duration to identify patterns early.
- Flexible claims handling rules: The system should support policy changes during the claims lifecycle, such as plan upgrades or cancellations, without creating operational conflicts or manual intervention.
The key shift is that claims management needs to move from a linear, process-driven function to a more connected, real-time service layer that supports both operational efficiency and customer experience.
Regulatory Considerations for Subscription Auto Insurance
Subscription auto insurance introduces flexibility on the product side, but regulatory frameworks are still largely built around fixed-term policies. That creates a gap insurers need to manage carefully when designing and launching this model.
The goal is not just compliance, but ensuring that flexibility does not create regulatory risk, filing delays, or approval challenges across states.
Key Areas Insurers Need to Address
- Monthly renewal structure: Regulators may require clarity on how continuous monthly renewals are defined, whether they are treated as new policies, extensions, or a rolling contract. This impacts filings, disclosures, and compliance obligations.
- Cancellation and notice requirements: Even if the product allows easy cancellation, insurers must still comply with state-specific notice periods, non-renewal rules, and consumer protection requirements.
- Minimum coverage duration rules: Some jurisdictions may not fully support very short-term or highly flexible coverage structures. Insurers need to ensure the product aligns with minimum term expectations where applicable.
- Disclosure for bundled offerings: When insurance is packaged with vehicle access or other services, regulators may require clear separation and disclosure of:
- insurance vs non-insurance components
- pricing breakdown
- coverage terms and conditions - Filing and approval complexity: Subscription models often involve new pricing structures, billing logic, and product definitions. This can lead to:
- more detailed filings
- higher likelihood of objections
- longer approval timelines
Customer Strategy for Subscription Auto Insurance
Subscription auto insurance requires a different approach to customer strategy. Success depends not just on who you target, but on how the product fits into changing mobility needs and how clearly that value is delivered over time.
The model works best with customers whose mobility patterns are variable rather than fixed, and who are open to managing coverage as part of an ongoing service.
Target Segments to Focus On
Insurers should prioritize segments where variability in usage creates a natural fit:
- Urban and semi-urban drivers: More likely to have inconsistent driving patterns and changing vehicle needs
- Younger, digitally comfortable users: More open to managing products through apps and recurring payment models
- Subscription-oriented consumers: Already familiar with managing services through monthly payments
- Users of car subscription or leasing platforms: More likely to adopt bundled offerings where insurance is part of a broader package
- Convenience-driven, higher-income segments: Less price-sensitive and more focused on ease of management
How Insurers Should Approach Go-to-Market
Subscription auto insurance requires a different go-to-market approach compared to traditional policies.
- Embedded and partner-led distribution is a strong fit: The model aligns naturally with OEM platforms, vehicle subscription providers, and mobility ecosystems where insurance can be offered as part of a broader service
- Direct-to-consumer works when the product is simple: Clear pricing tiers and minimal configuration are critical for direct channels
- Acquisition should focus beyond price: Customers evaluate onboarding experience, billing clarity, and ease of use, not just premium levels
What Drives Customer Adoption in This Model
Adoption depends on how clearly the product fits into real usage and expectations:
- Clarity in what is included vs excluded: Customers need a clear understanding of what the monthly price covers, especially in bundled offerings
- Confidence in making changes without penalty: The ability to switch plans or vehicles without unexpected costs builds trust
- Consistency across the lifecycle: The experience from onboarding to claims should feel aligned, not fragmented
- Perceived control over the product: Customers should feel they can adjust coverage as their needs change without added complexity
Why Retention Matters More Than Acquisition
In this model, long-term value is driven more by how long customers stay than how many are acquired.
Insurers should actively manage:
- early churn, especially in the first few months
- engagement through ongoing interaction points
- clear pathways for plan upgrades or transitions
- service quality across claims and support
A customer who stays longer contributes significantly more value than one who frequently enters and exits.
When Subscription Auto Insurance Makes Sense for P&C Insurer
Subscription auto insurance is not the right fit for every insurer or every market. Before building it, insurers should assess whether the model aligns with their customer base, product design, operating model, and technology capabilities.
Decision Framework for Insurers
| Decision Area | What to Assess | Strong Fit Indicators | Warning Signs |
|---|---|---|---|
| Market fit | Whether customer demand supports a flexible monthly model | Urban or hybrid-driving markets, digital-first users, demand for convenience and lower commitment | Customers still prefer fixed annual policies and traditional billing |
| Product fit | Whether the product can be simplified into a recurring subscription structure | Standardized coverage tiers, simple monthly packaging, bundling potential | Highly customized products, complex rating structures, niche underwriting needs |
| Operational readiness | Whether internal teams can support frequent changes and continuous servicing | Ability to handle monthly billing, mid-cycle changes, fast activation, and self-service support | Heavy manual processing, slow servicing workflows, limited billing flexibility |
| Technology readiness | Whether core systems can support a subscription-based model | Modular PAS, recurring billing, real-time pricing, API integrations | Legacy systems built around fixed terms, batch processing, and limited integration |
| Regulatory fit | Whether the product can work within state-specific compliance requirements | Clear filing path, manageable disclosure needs, flexibility within target states | Unclear treatment of rolling renewals, strict cancellation rules, complex filing risk |
This model makes the most sense when there is alignment across all five areas. If one or two areas are weak, insurers may still explore the concept, but the launch path will likely be slower and more complex.
Strategic Takeaway
Subscription auto insurance is not just a product innovation. It is a business model decision. The stronger the fit across market demand, product structure, operations, technology, and compliance, the more realistic the opportunity becomes.
Conclusion
Subscription auto insurance is not just a different way to structure pricing. It requires insurers to rethink how products are designed, priced, operated, and supported across the full lifecycle.
For insurers exploring this model, the challenge is not whether the concept works. The real challenge is whether the organization is ready to support the coordination it requires across pricing, operations, technology, underwriting, and compliance.
Insurers need a structured approach to assess where the model fits, what capabilities need to change, and how to build it in a way that can scale without creating operational friction.
Insurance strategic consultants such as Practo Insura help insurers define the right model, align internal capabilities, and build the foundation needed to support subscription auto insurance effectively.
In the end, subscription auto insurance will not be defined by how innovative it looks on the surface. It will be defined by how well it is designed and executed behind the scenes